Start here
If you’ve found cracking that might be subsidence, the next question is almost always about insurance. The good news is that most UK buildings insurance policies do cover subsidence. The less welcome news is that the cover comes with a higher excess and a set of exclusions that catch people out. Here’s how it typically works.
- Main building
- Patio & paths
- Boundary wall
- Garage
- Patio & paths
As ever, policies differ. Treat this as general guidance and check your own policy wording.
Contents8 sections
What’s usually covered
Standard buildings insurance normally covers damage to the main building caused by:
- Subsidence — the ground beneath the foundations moving down;
- Heave — the ground moving up;
- Landslip — the ground moving down a slope.
Cover typically includes the investigation into the cause, measures to stabilise the building, and repairs to the damage. On a straightforward claim the insurer usually appoints a loss adjuster or specialist subsidence contractor to manage the whole process. We walk through that in how subsidence claims actually work.
Contents insurance is separate and generally doesn’t cover subsidence damage to the structure.
The subsidence excess
Subsidence claims almost always carry a much higher excess than other claims — commonly around £1,000, and sometimes more. That’s the part of each claim you pay yourself. Check your schedule, because it varies between insurers and policies.
What’s usually excluded
The exclusions matter as much as the cover. Common ones include:
- Settlement — normal bedding-down of a newly built structure, or of new extensions.
- Damage to outbuildings, patios, paths, drives, walls, gates and fences — unless the main house is damaged by the same cause at the same time.
- Movement of solid floor slabs, unless the foundations beneath the load-bearing walls are damaged at the same time.
- Coastal or river erosion.
- Damage caused by demolition, structural alteration or repair work.
- Faulty design, materials or workmanship.
- Damage that started before you took out the policy.
How long do you have to declare subsidence?
There isn’t a single fixed period. What matters is the question the insurer asks. Some ask whether the property has ever suffered subsidence, heave or landslip, or been underpinned. Others ask about a set period, such as the last ten years, or whether there are cracks or signs of movement now.
Under UK consumer insurance law, you have a duty to take reasonable care to answer the insurer’s questions accurately. If you answer incorrectly, even innocently, the insurer may reduce a claim, refuse it, or in serious cases cancel the policy. So answer exactly what’s asked, and if you’re unsure whether something counts, say so and let the insurer decide.
Buying a house that has had subsidence
A past claim doesn’t make a house unbuyable. It does mean you need the right information before exchange:
- The claim history — when the movement happened, what caused it, and what was done.
- A Certificate of Structural Adequacy, or equivalent sign-off confirming the repairs and that the movement has been stabilised.
- Any monitoring records and the engineer’s or adjuster’s reports.
- Whether the current insurer will transfer cover to you. Many insurers will offer continued cover to a buyer on a property with a subsidence history, which can be far easier than finding new cover elsewhere. Ask early.
- Your lender’s position, as some will want to see the paperwork before lending.
We cover the effect on value separately in does subsidence devalue a property?.
When the insurer and you disagree
Disputes usually centre on the cause of the damage, whether it falls within an exclusion, or the scope of repair. If you can’t resolve a complaint with the insurer, you can take it to the Financial Ombudsman Service. Clear technical evidence about the cause and extent of movement often decides the outcome.
How we help
With extensive complex claims experience, we provide independent subsidence assessment and insurance claims consultancy for policyholders — establishing cause, challenging a declined or under-scoped claim, and checking that the repair actually matches the problem. Tell us what’s happening.
From the survey archive
Cracks outside and in.
A stepped crack in a garden retaining wall and a long ceiling crack, from our survey archive. Cracks like these have several possible causes and do not on their own confirm subsidence.
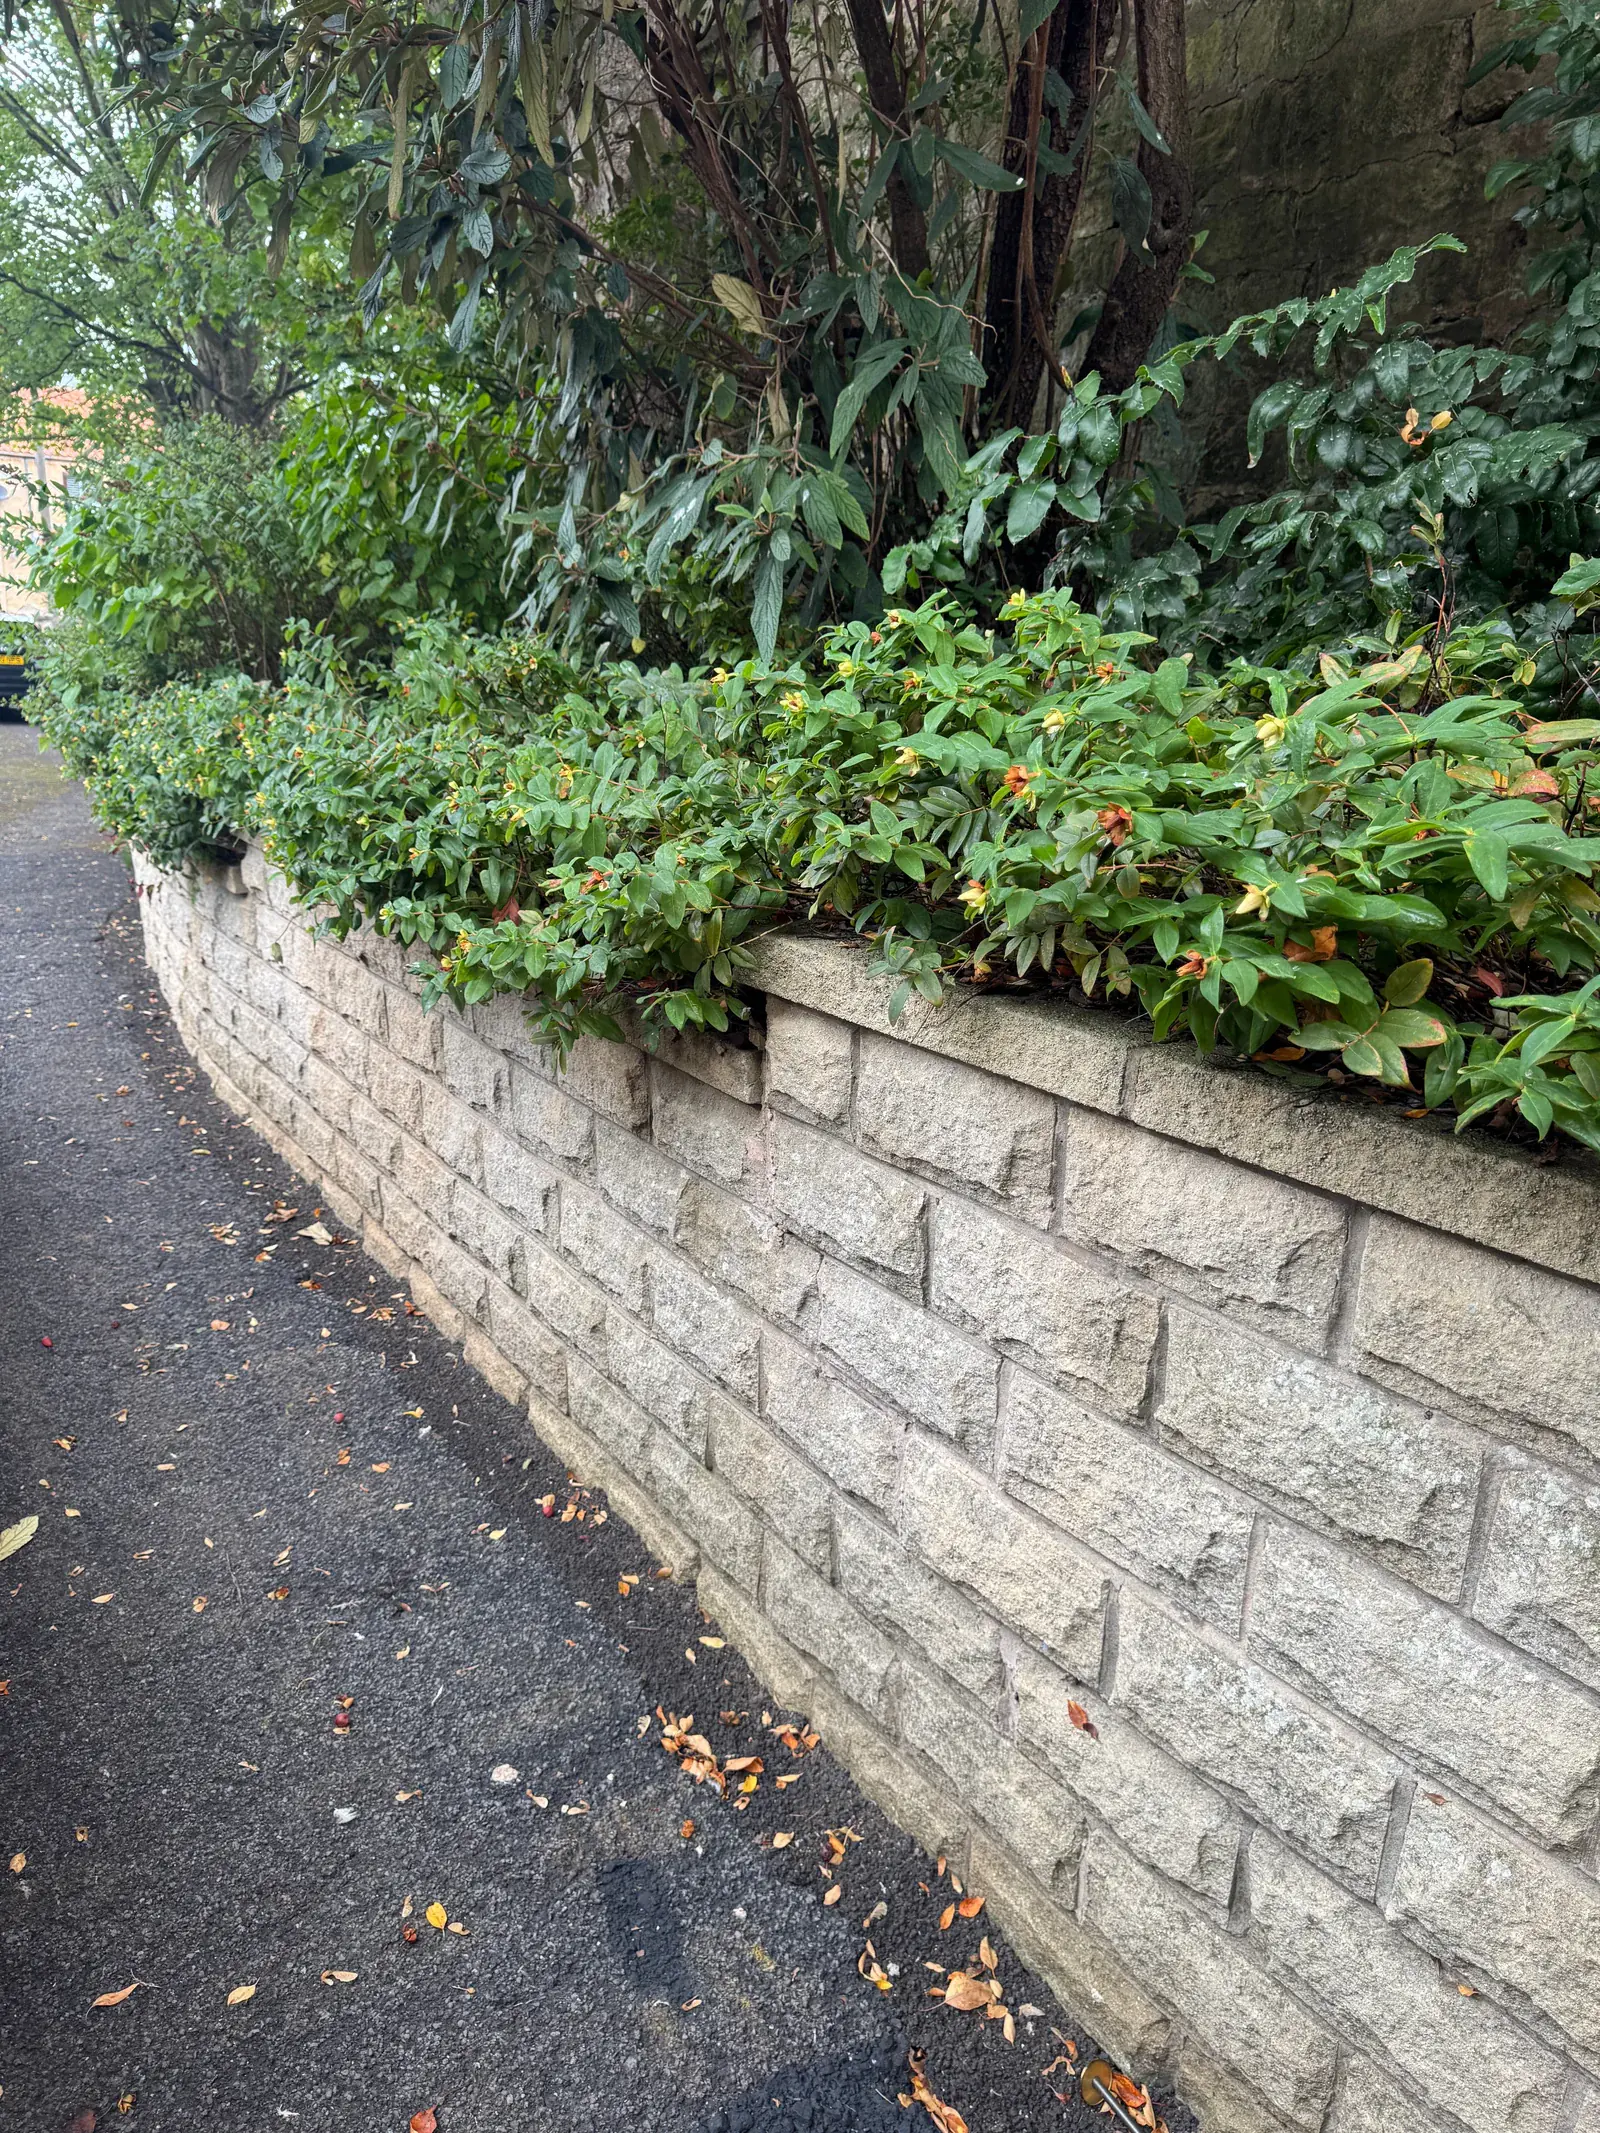
Cracked garden retaining wall
A stepped crack and open joints in a garden retaining wall.
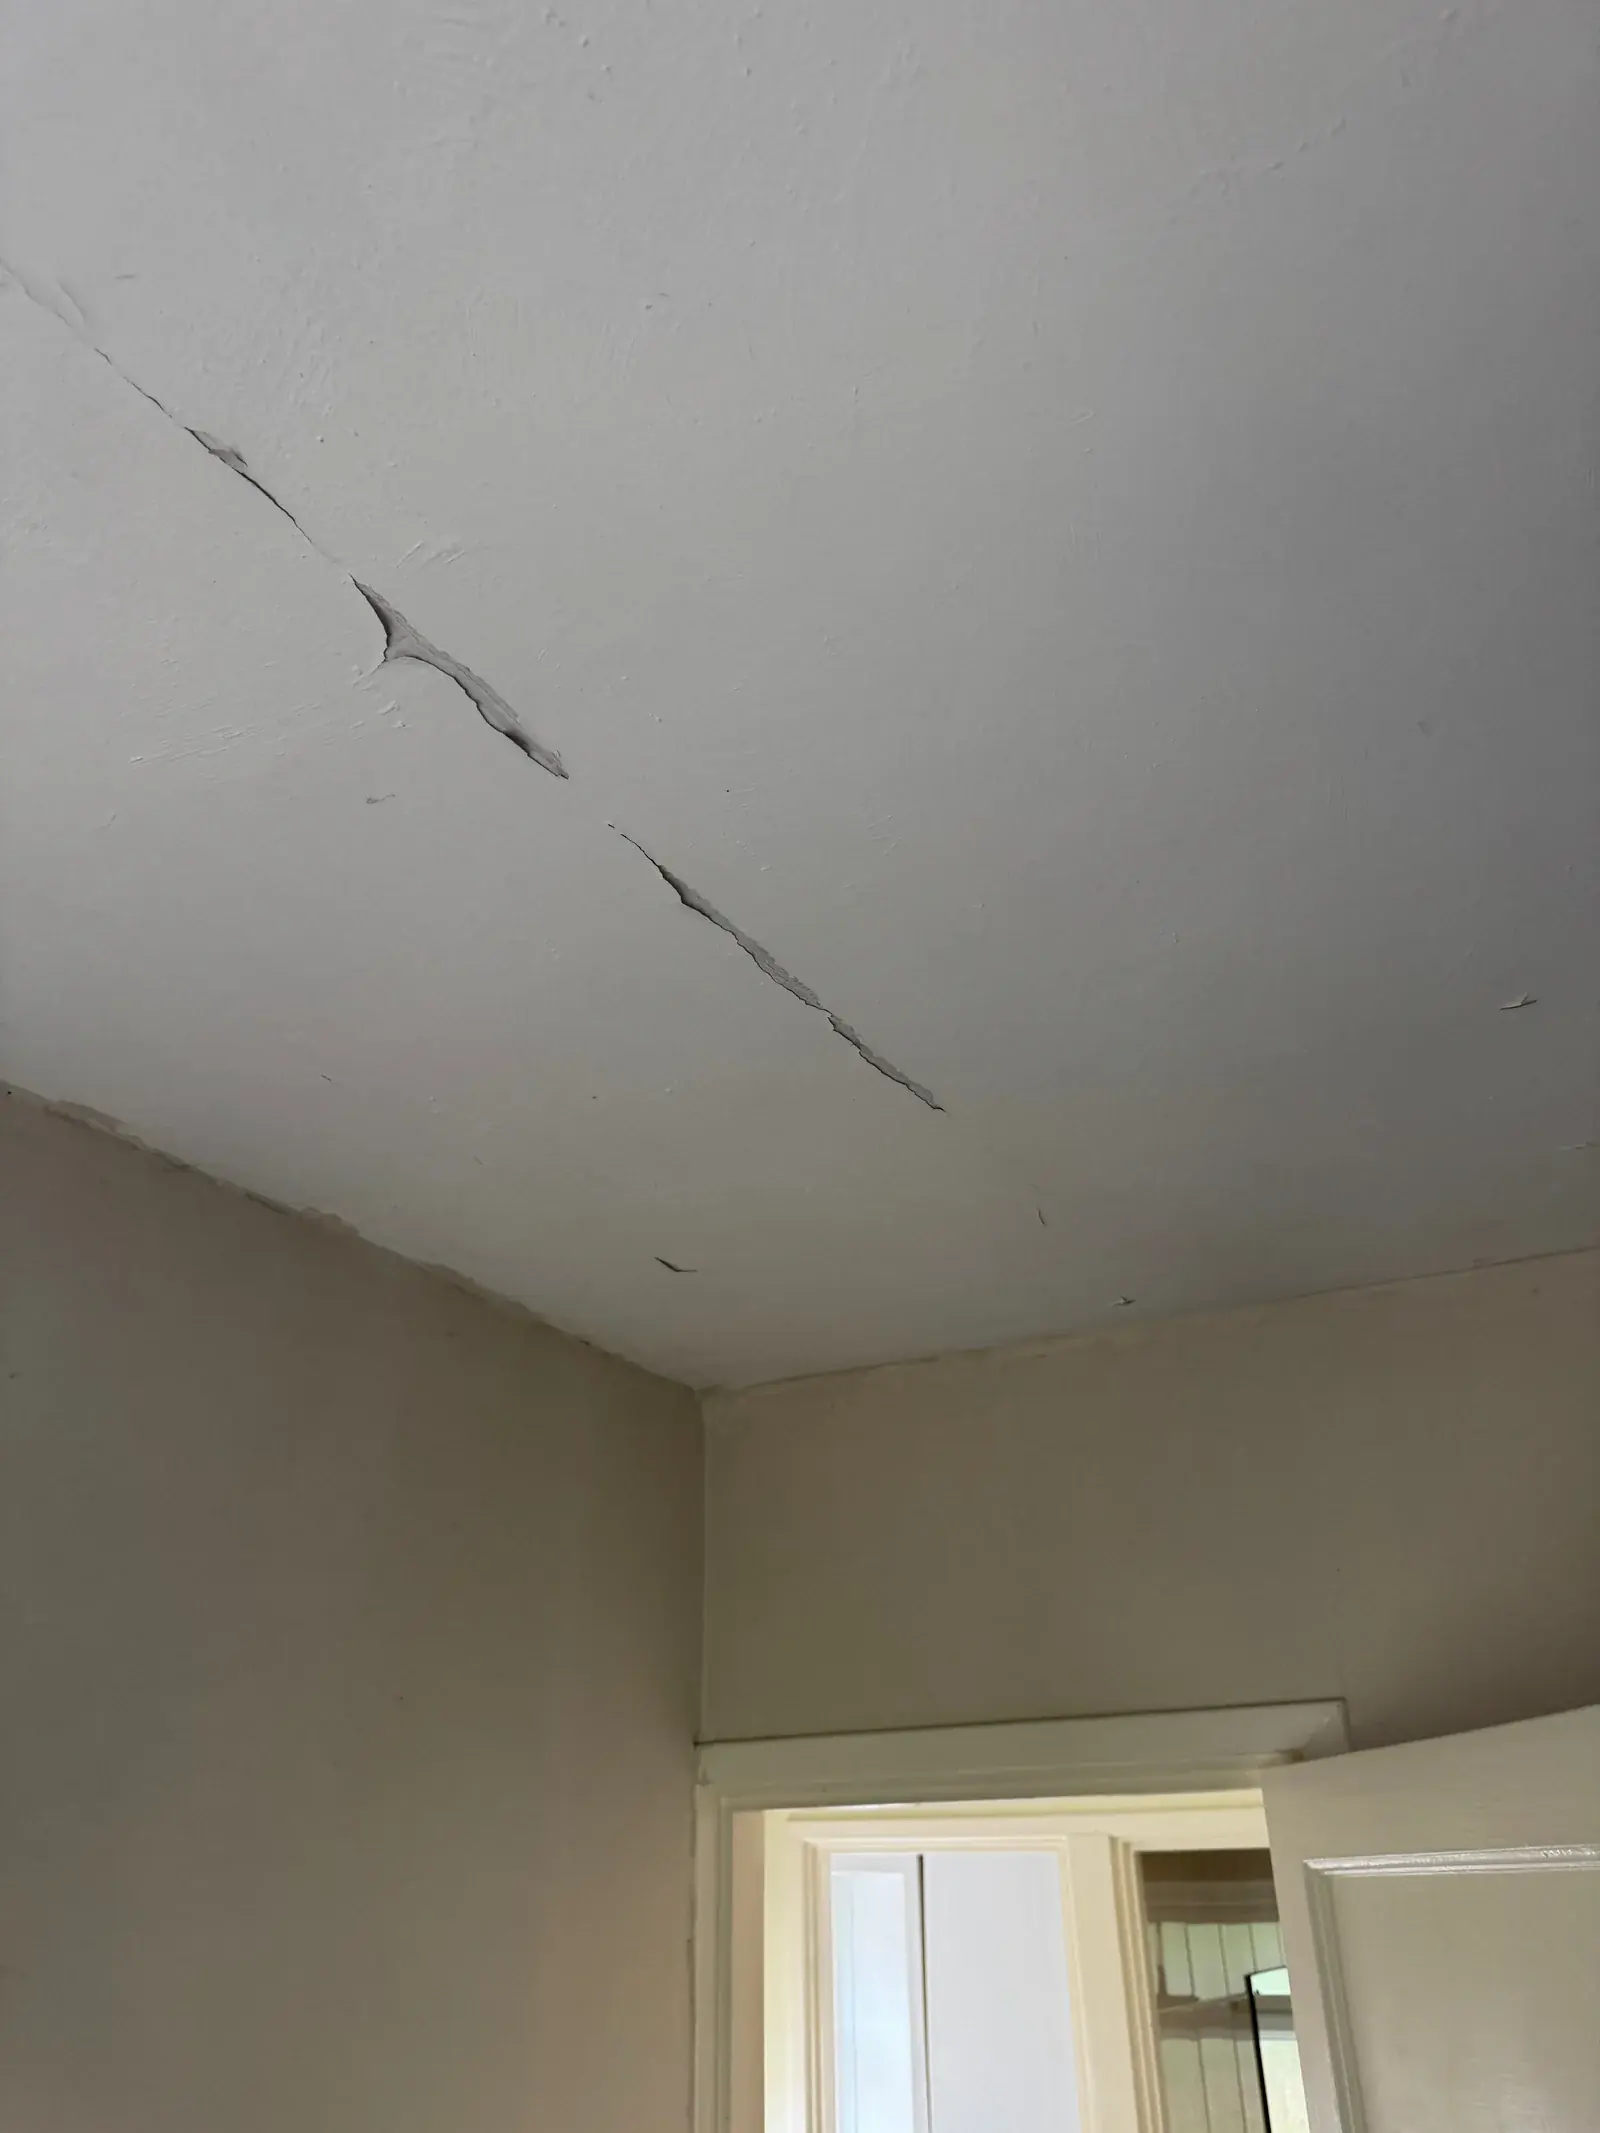
Crack and lifting finish across a ceiling
A long ceiling crack with lifting paint along parts of its length.
Photographs from our survey archive.
Explore the full photograph collectionRelated service
Independent expert support for policyholders: reinstatement cost assessments, claim validation, technical evidence suitable for an Ombudsman complaint and post-repair inspection.
About this serviceRequest an insurance claims consultancy quoteOr call 01484 218579
RICS-regulated firm no. 9317773
Places where this matters
Towns on the coalfields.
Each of these town pages sets out the local coal mining history and when to ask for a coal mining report.
Free tools
Check your own property.
Sources and further reading
- Consumer Insurance (Disclosure and Representations) Act 2012 — legislation.gov.uk — the duty to take reasonable care when answering insurers’ questions
- Insurance complaints — Financial Ombudsman Service
- How to complain — Financial Ombudsman Service