Independent building advice · Huddersfield, West Yorkshire
Insurance claims consultancy
When your home is damaged — by fire, flood, escape of water, subsidence or impact — you are suddenly negotiating with an insurer whose representatives handle claims every day.
The scope and fee are agreed before you commit.
- Line-by-line
- Dated photo evidence
- Omitted from scope
01 / Your situation
Who this service is for
Most policyholders go through a claim once or twice in a lifetime.
This service puts genuine claims-side experience on your side. We draw on experience handling large loss and complex claims across subsidence, fire, flood, escape of water, escape of oil, impact and structural losses. That means knowing how claims are scoped, costed, validated and settled from the inside.
The role here is independent, whichever way the evidence points. We give an honest assessment of what your policy entitles you to, what the reinstatement genuinely costs and whether the offer is fair.
We provide independent technical evidence and advice: reports on the cause and extent of the damage, the scope and cost of the reinstatement, and the quality of repairs. We do not notify, negotiate or settle claims on anyone’s behalf, so you, or your solicitor, stay in charge of the claim itself.
- Policyholders with a live claim who feel out of their depth or under-settled
- Homeowners whose claim has been declined and who want an independent technical review
- Anyone preparing a Financial Ombudsman Service referral who needs the technical case set out properly
- Policyholders whose repairs are complete but appear defective or incomplete
What the service covers
- An independent technical report on the cause and extent of the damage
- Reinstatement cost assessment using Xactimate — an estimating platform widely used across the UK claims industry
- Independent review and validation of insurer and contractor scopes
- Advice on the technical evidence your claim needs, so you can present and negotiate it yourself from an informed position
- Technical reports and evidence you can rely on in a Financial Ombudsman Service referral
- Post-repair inspection and validation — confirming works match the agreed scope and are of acceptable quality
- Photographic and 360° condition records — dated, referenced evidence for the claim file
Scope limits
- Legal advice — where a claim needs a solicitor, the report will say so
- Loss assessing or claims negotiation: notifying claims, completing claim forms and negotiating settlement with your insurer on your behalf are FCA-regulated activities that we deliberately do not undertake. You stay in control of your own claim, armed with independent expert evidence
- Guaranteed outcomes — the opinion follows the evidence, including where the evidence supports the insurer’s position
From the survey archive
Evidence beneath the finishes.
Staining inside a sink cabinet, a moisture check above a skirting board, darkened boards beside a bathroom fitting, exposed boards and pipe connections beneath an opened floor, staining at a rooflight corner and deteriorated bath sealant, from our survey archive.
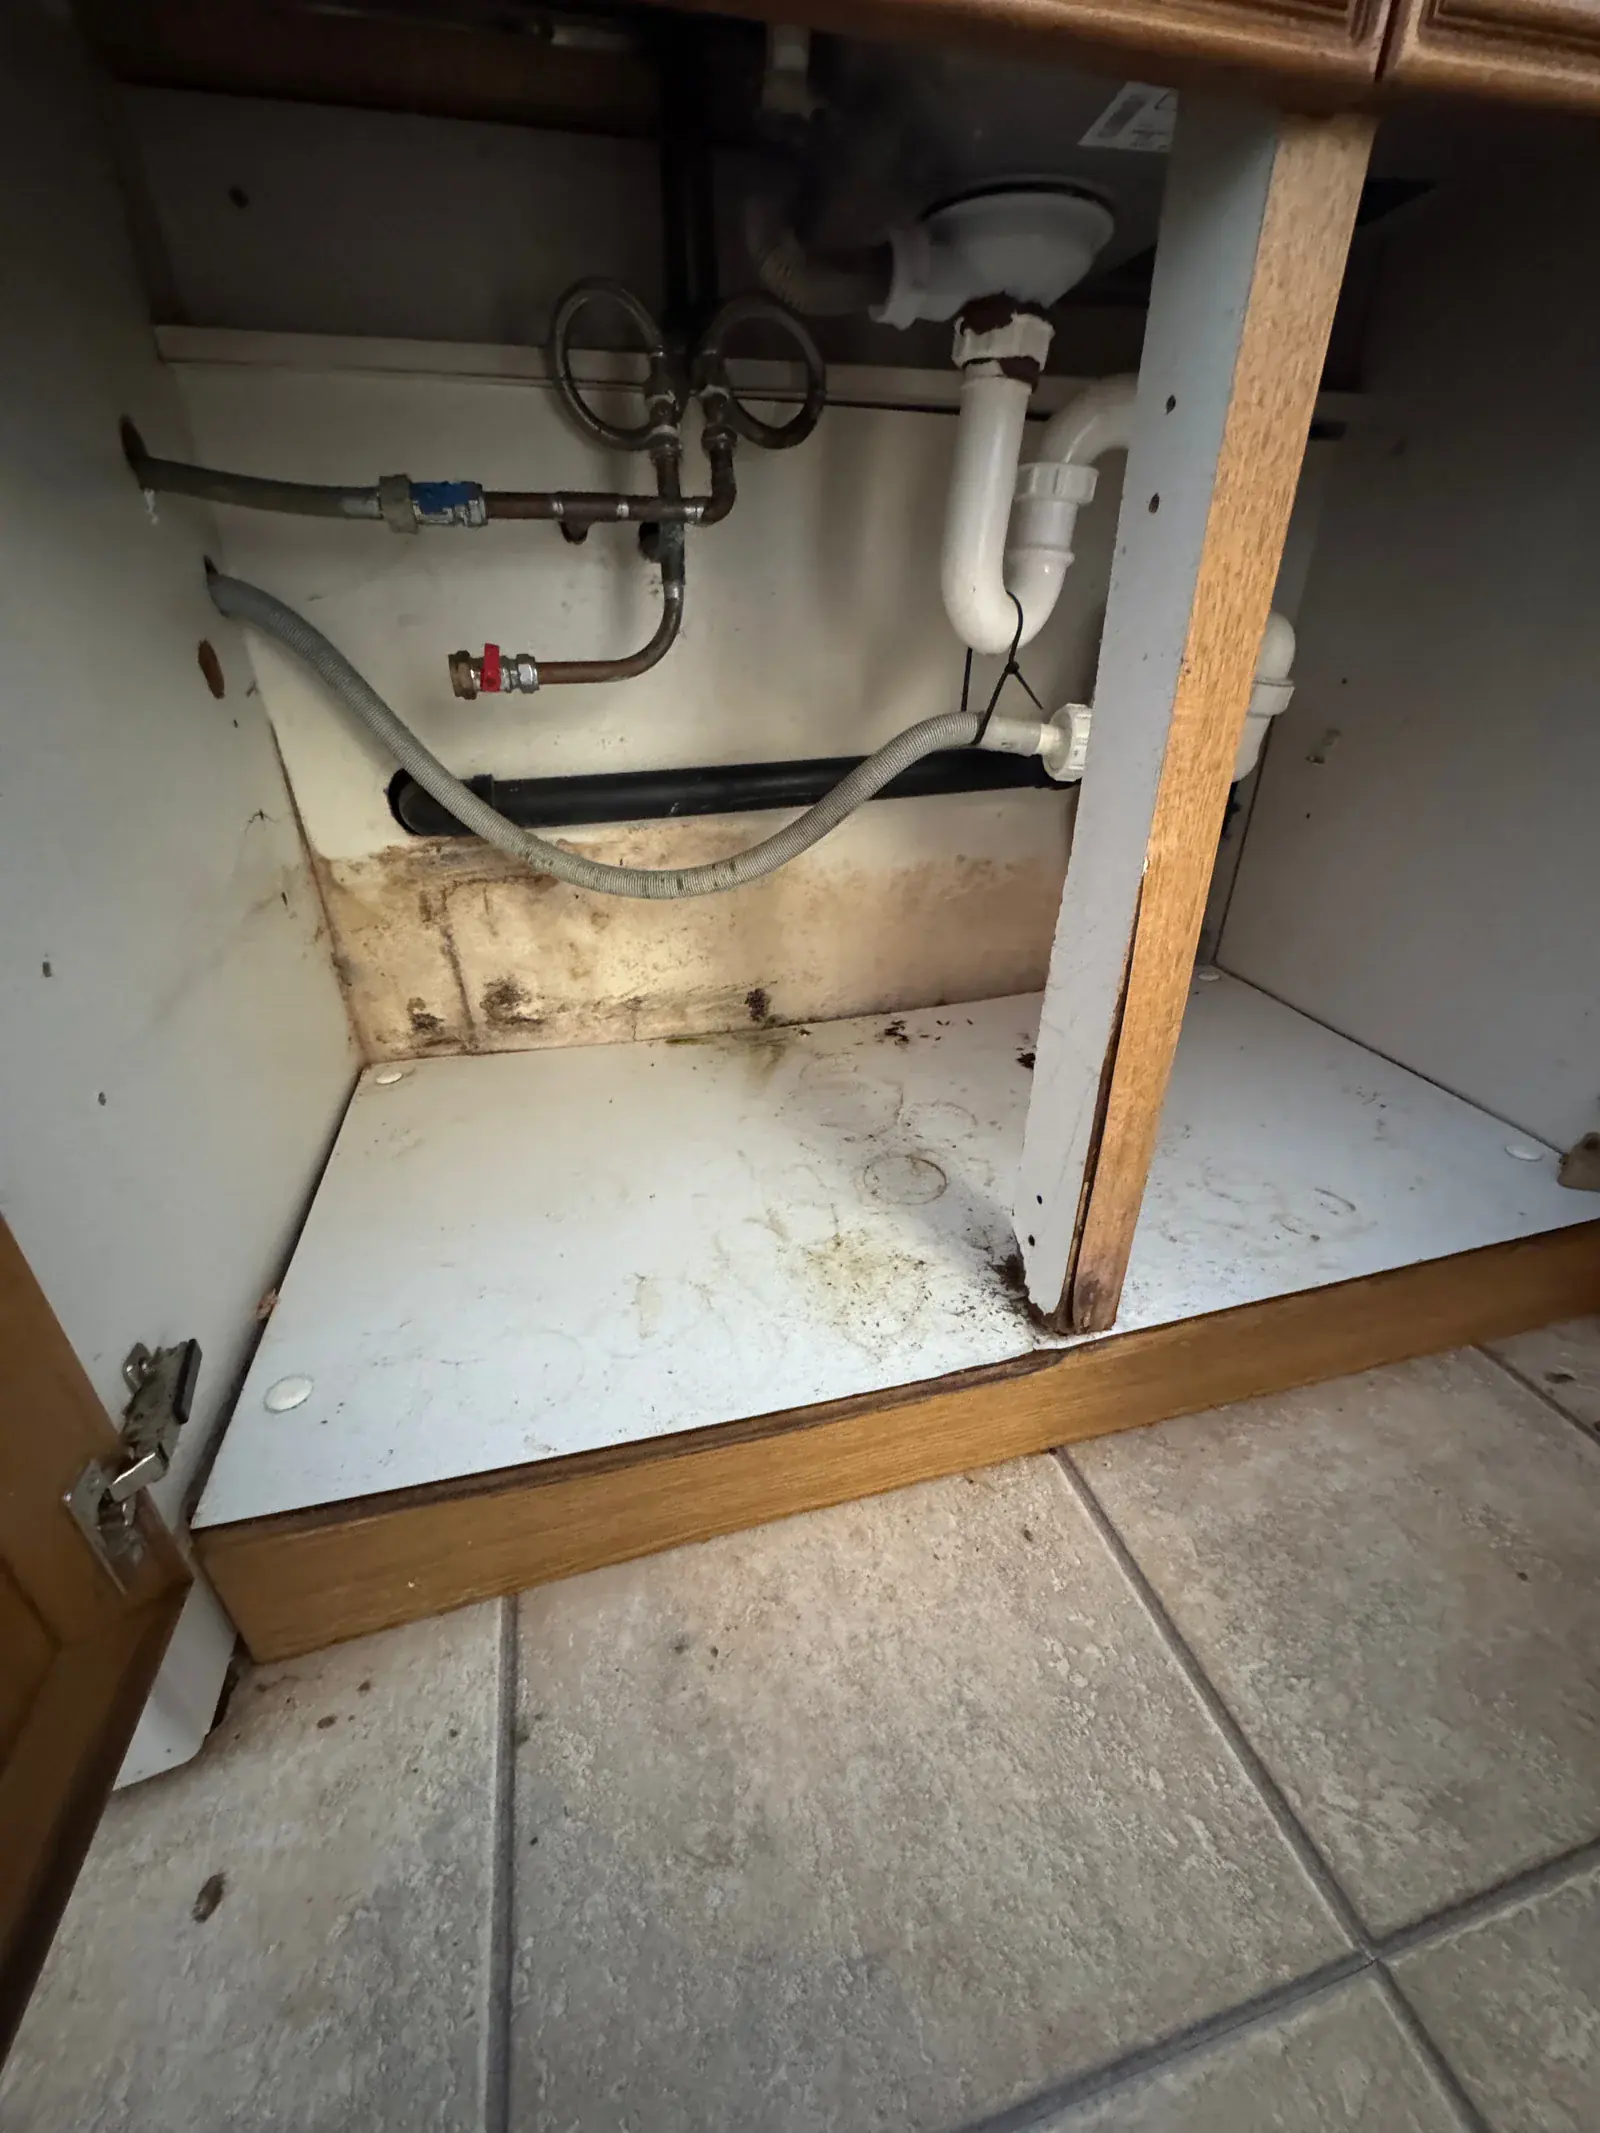
Staining inside a sink cabinet
Staining on the base and back of the cabinet beneath the sink pipework.
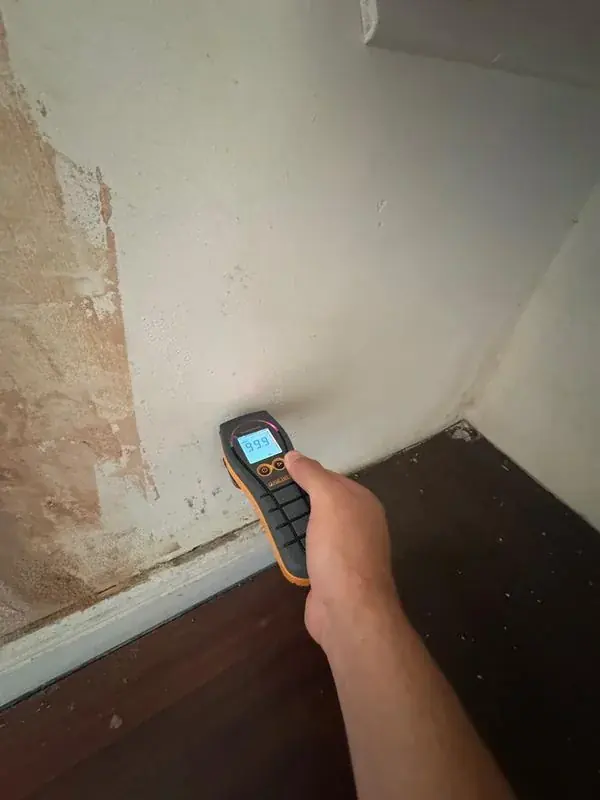
Moisture check above a skirting board
A moisture meter held against marked plaster above the skirting board.
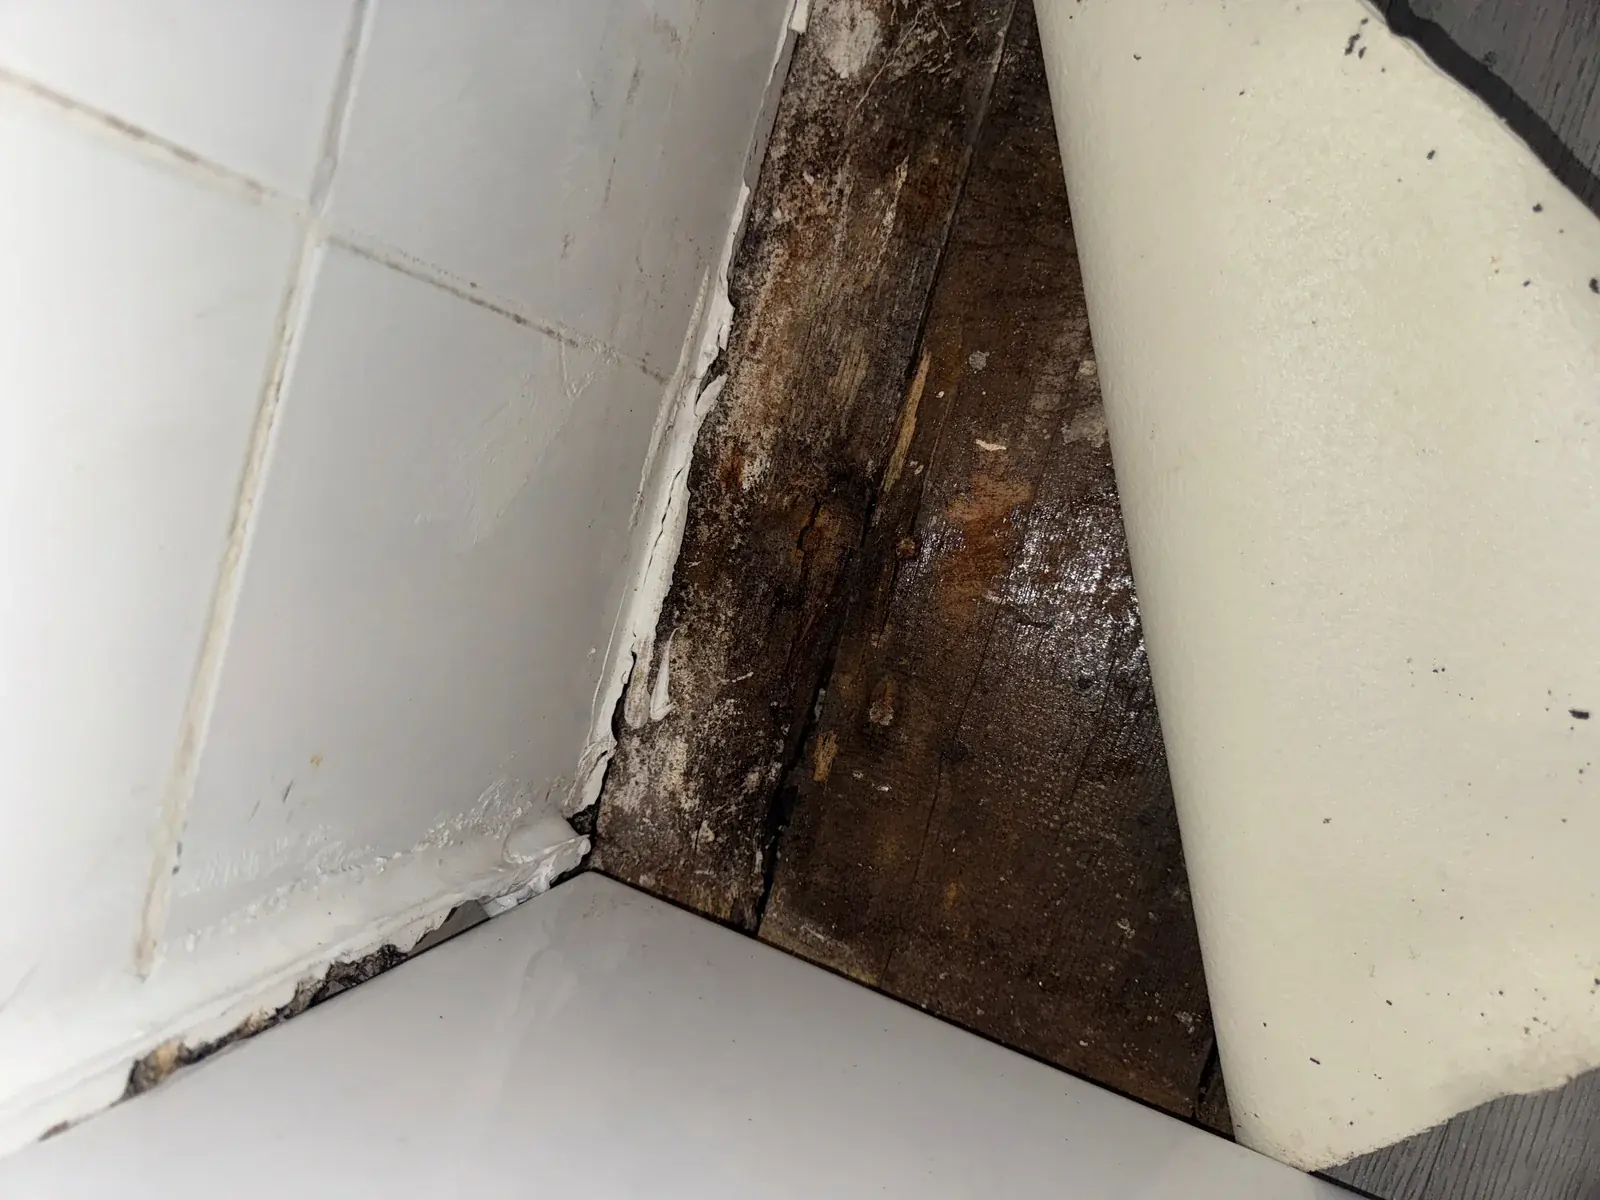
Darkened boards at a bathroom floor edge
Darkened floorboards beneath a lifted covering beside the bathroom wall and sanitary fitting.
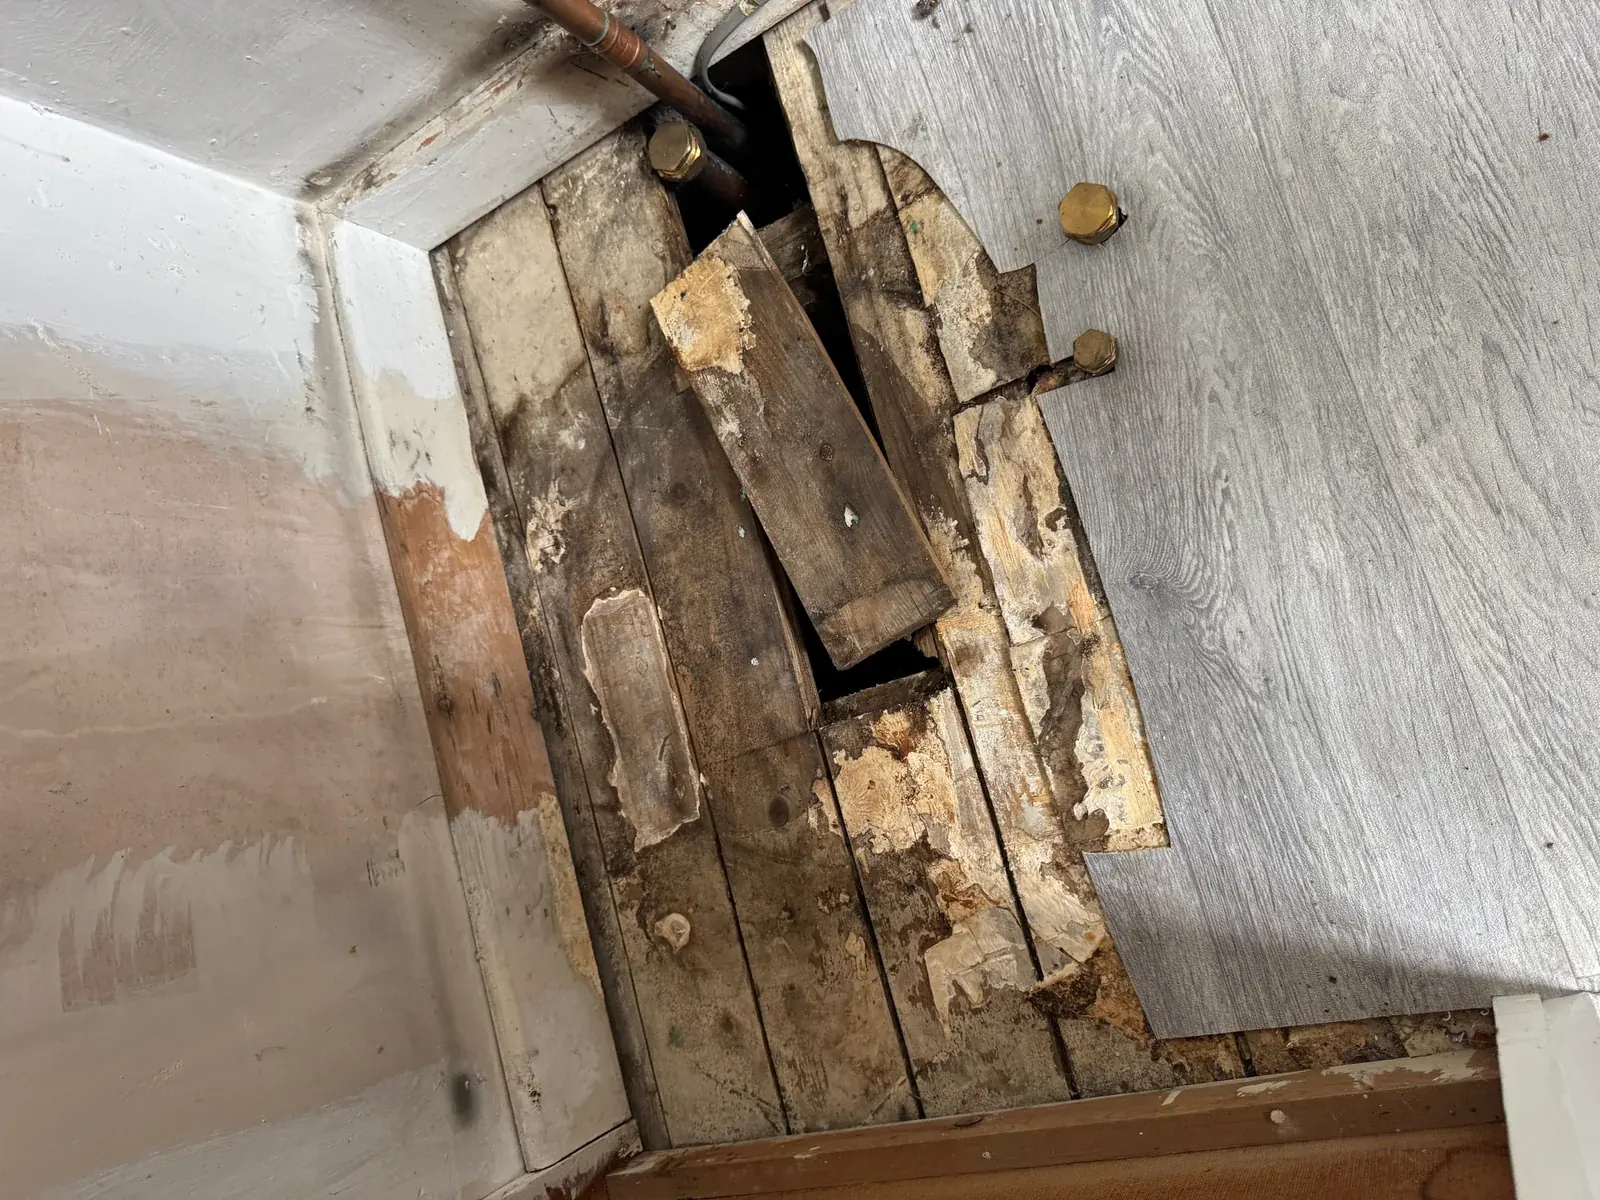
Exposed boards and pipe connections
Exposed boards, gaps and plumbing connections beneath an opened section of floor.
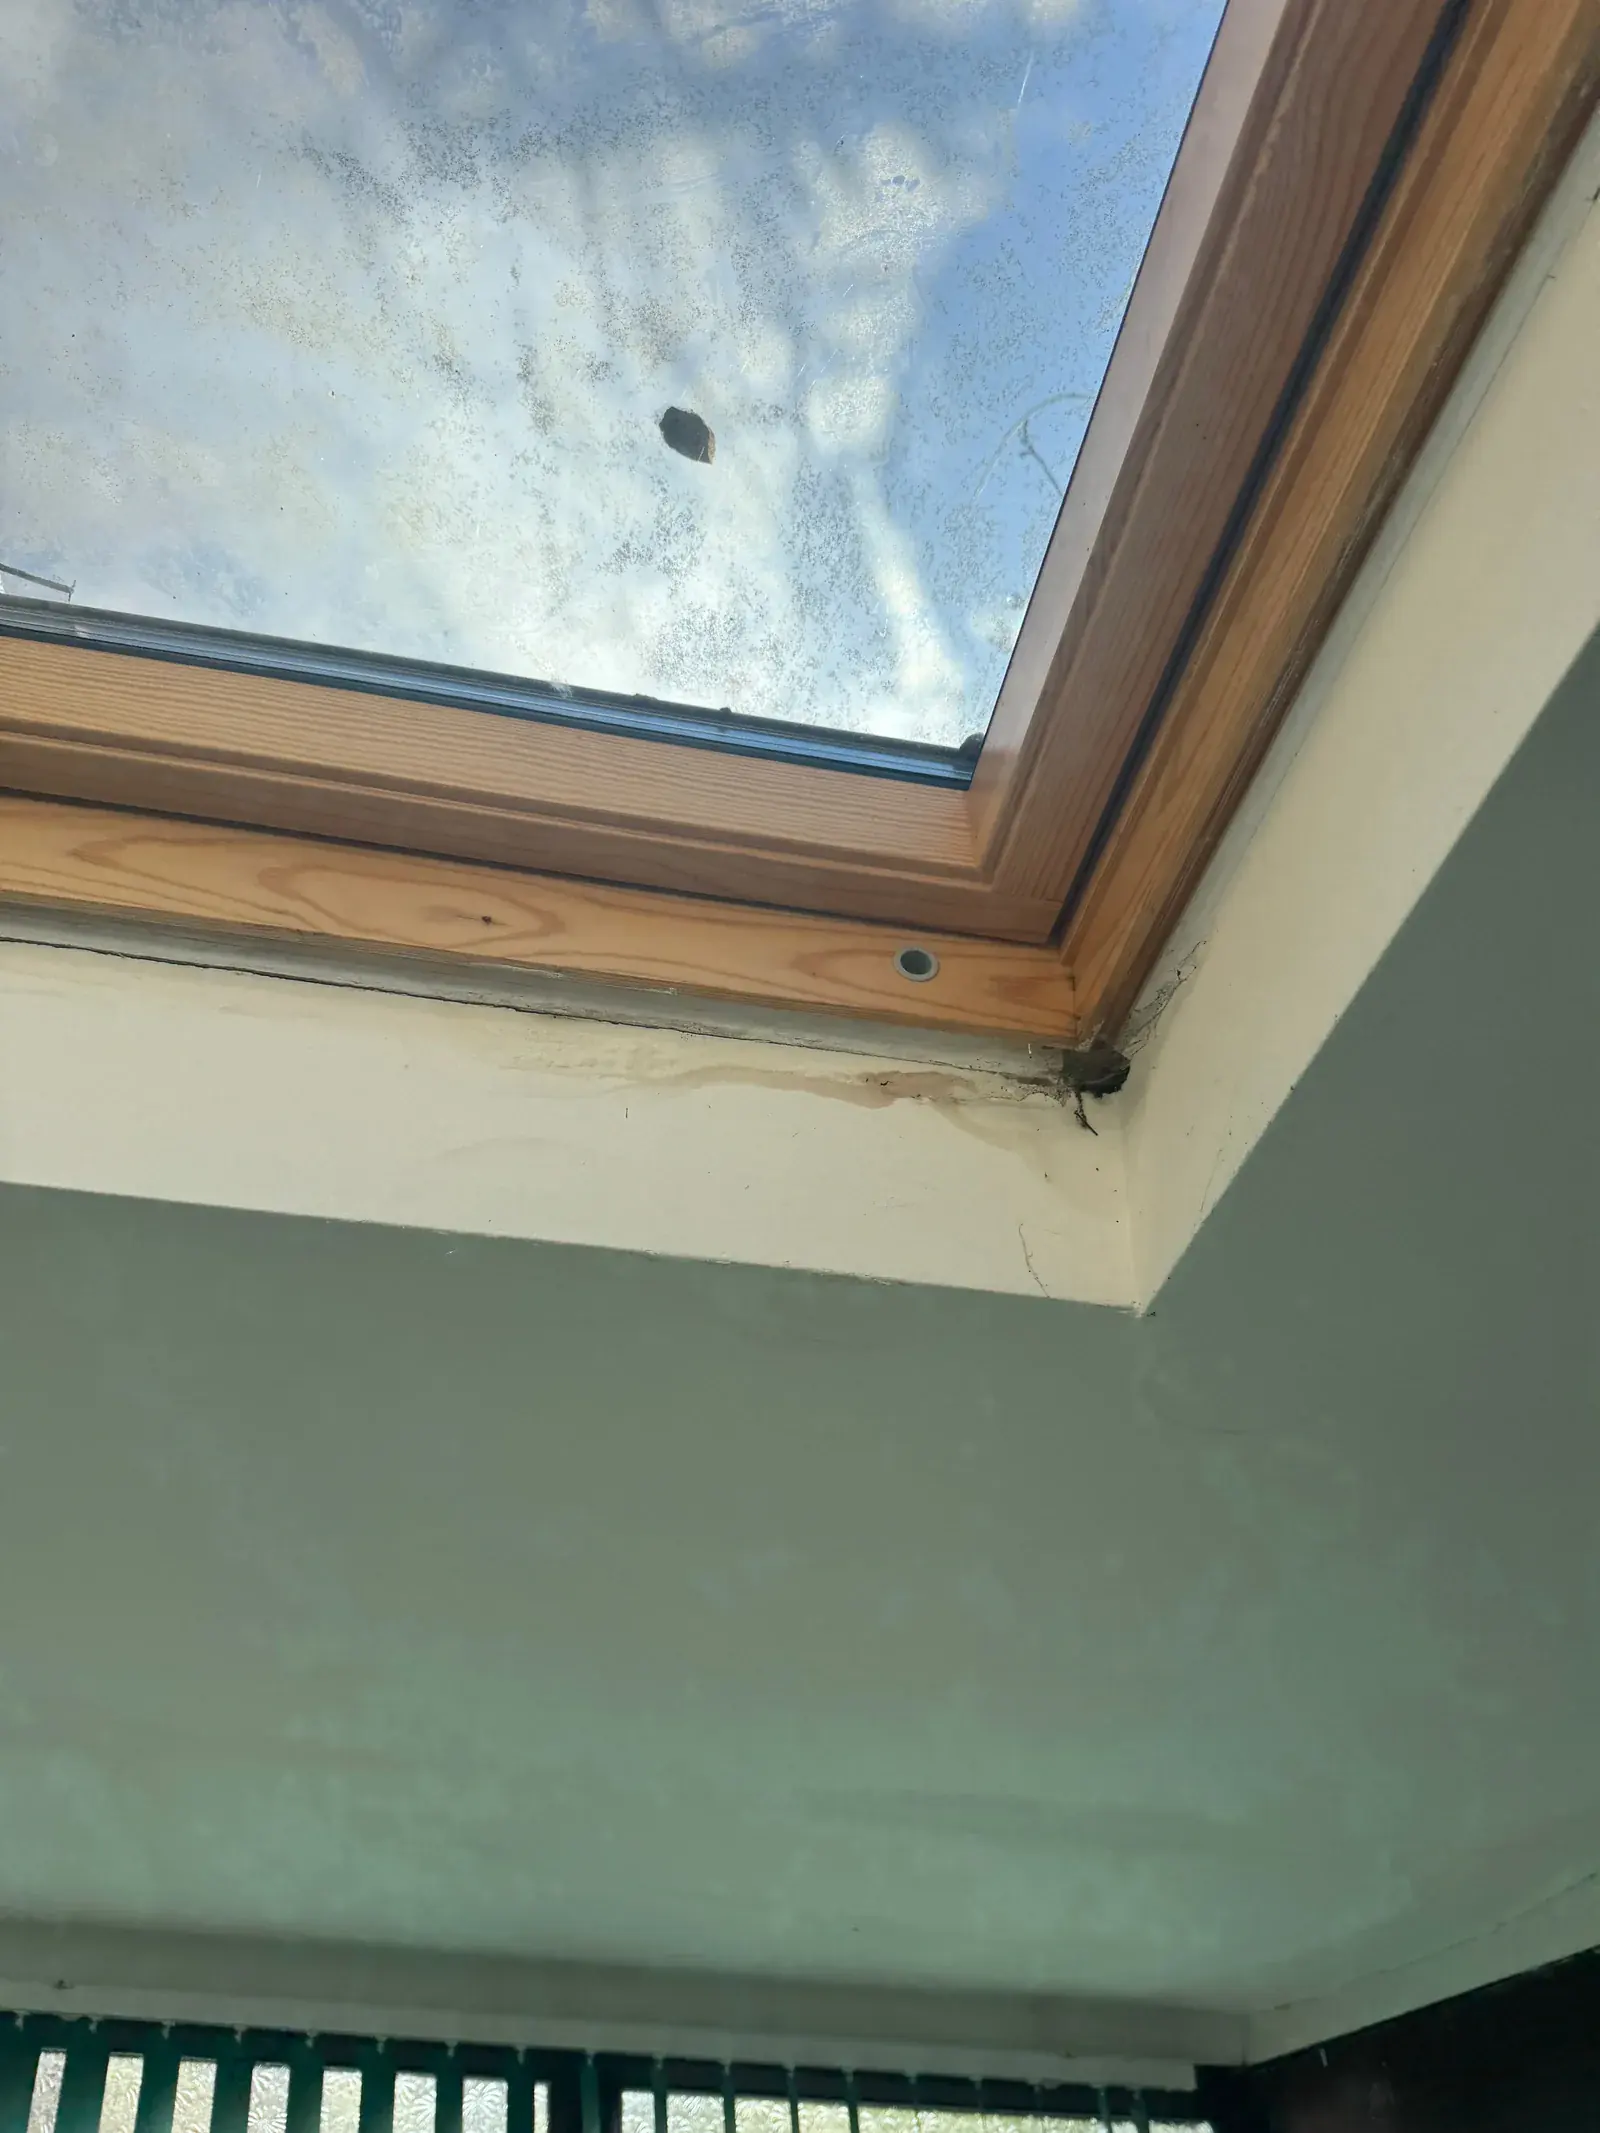
Staining at the lower corner of a rooflight
Brown staining across the plaster at the lower corner of a rooflight.
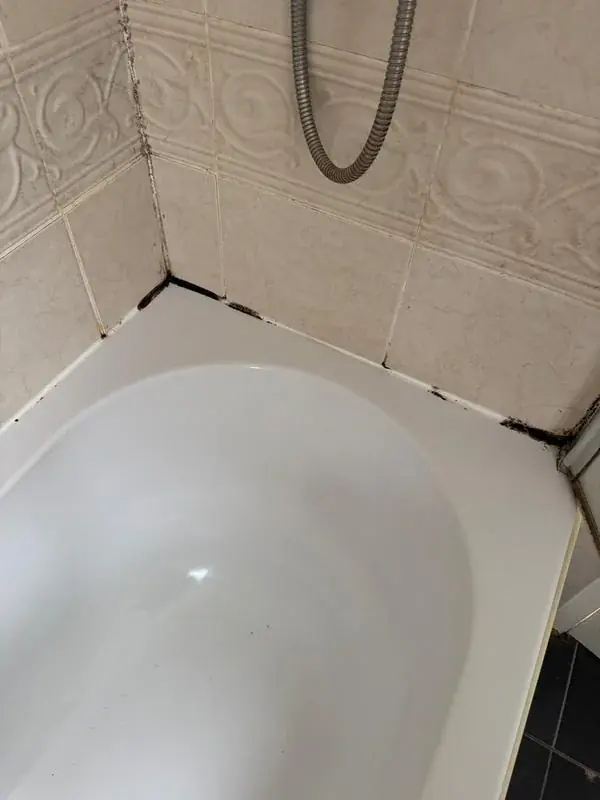
Deteriorated sealant around a bath
Darkened, incomplete sealant along the bath-to-tile joint and corner.
Photographs from our survey archive.
Explore the full photograph collectionOur approach / Evidence before conclusions
How it works
- 01
Initial review
A confidential discussion of the claim, the correspondence to date and what you are trying to achieve — with an honest early view of whether independent input will help.
- 02
Inspection and assessment
Inspection of the damage or repairs and a review of the claim file, scopes and costings.
- 03
Report
A clear technical report you can put to the insurer, loss adjuster or Ombudsman — evidence, analysis, and what a fair outcome looks like.
- 04
Ongoing support
Follow-up technical input as the claim progresses, including review of revised scopes and offers, and post-repair validation.
Condition and loss are captured before evidence disappears.
Damage is tested against the reported event and policy position.
The repair scope follows the evidence — not assumptions.
Honesty cuts both ways: if the insurer’s position is technically sound, you will be told so before spending money contesting it. That candour is exactly what makes the reports credible when they do show that an offer falls short.
Before you decide
A clearer brief.
A useful answer.
Tell us what you have noticed, what has already been checked and what decision you need to make. We’ll confirm where we can help.
Discuss your propertyWhat is Xactimate and why does it matter?
Xactimate is an estimating platform widely used across the UK claims industry to cost reinstatement works. Producing your assessment in the same platform means the insurer’s team can compare line by line — which makes under-scoping much harder to sustain.
Can you deal with the insurer for me?
No — deliberately. Notifying claims, completing forms and negotiating settlement on a policyholder’s behalf are regulated activities requiring FCA authorisation (or an RICS DPB licence), and we do not take them on. What you get instead is independent expert evidence and appraisal — produced to the same standard the insurer’s own experts work to — so that you, or your solicitor, can negotiate from strength.
Is it worth challenging a declined claim?
Sometimes — declinatures on causation grounds (for example “not subsidence” or “wear and tear”) can be technically wrong. An initial review will give you a straight answer on the strength of your position before you commit to a full report.
Could you be working for my insurer as well?
Not on the same claim, except in the limited circumstances RICS allows. Every new job is checked for conflicts of interest before it is accepted, as RICS requires of regulated firms, and we confirm in writing who we are acting for. We do not act for both a policyholder and their insurer on the same claim unless the conditions in RICS’s conflicts of interest standard are met, including the prior informed consent in writing of everyone affected.
Can you inspect repairs my insurer’s contractors carried out?
Yes — post-repair inspection compares the completed works against the agreed scope and acceptable workmanship standards, and documents any shortfalls for the insurer to address.
Follow the detail
Keep exploring.
The standards behind this service
- Insurance complaints
The free route for policyholders when an insurer won’t resolve a complaint.
- How to complain
How the complaints process works, including the insurer’s eight weeks to respond first.
- Consumer Insurance (Disclosure and Representations) Act 2012
The law on what policyholders must disclose when answering an insurer’s questions.
- Conflicts of interest
The RICS standard on identifying and managing conflicts of interest, which governs who we can act for.
A disputed claim?
Move the argument back to the building.
Send the property address and explain the situation. We’ll confirm the appropriate scope, fee and next step.
Request an insurance claims consultancy quoteOr call 01484 218579We aim to reply within one working day.