Start here
Subsidence is one of the most feared words in home ownership, and one of the least understood insurance processes. Having handled subsidence claims from the insurer’s side, we can tell you the process is more methodical — and usually less catastrophic — than most policyholders expect. Here is how a claim actually unfolds.
- Level monitoring
- Trial pit
- Foundation depth 0.9 m
- CCTV drain survey
Contents10 sections
Step 1: notification and triage
You notice cracking (or a drain survey, surveyor or builder flags it) and notify your buildings insurer. Subsidence is a standard insured peril in UK buildings policies, usually with a higher excess — commonly £1,000.
The Association of British Insurers suggests contacting your insurer as soon as you suspect subsidence, and lists the kinds of cracking worth reporting: cracks wider than about 3mm (roughly the thickness of a £1 coin), diagonal cracks that are wider at the top than the bottom, and cracks that show both inside and outside the house. Check your policy wording too. Garden walls, patios and drives are often not covered unless they are damaged at the same time as the house.
The insurer’s first job is triage: does the damage pattern actually suggest subsidence? A significant proportion of notifications are closed at this stage because the cracking is thermal, shrinkage or historic movement. That is not the insurer dodging the claim — most cracking genuinely is not subsidence.
What to do: photograph everything with a scale reference and dates before anyone visits. Do not redecorate over the cracks; the evidence matters.
If you have recently changed insurer
Subsidence develops slowly, so it isn’t always obvious which insurer should handle a claim when you’ve switched policies. Insurers that have signed up to the ABI’s domestic subsidence agreement follow it for change-of-insurer claims, and the Financial Ombudsman Service treats its principles as good practice. In outline: if the damage is notified within eight weeks of switching, the previous insurer usually handles it; between eight weeks and a year, the previous and current insurers share the cost; after a year, the current insurer deals with it. When you switch, answer the new insurer’s questions about cracking and subsidence carefully: under the Consumer Insurance (Disclosure and Representations) Act 2012 you must take reasonable care not to give a misleading answer.
Two special cases: escape of water and coal mining
If the movement was caused by an escape of water, such as a leaking drain or supply pipe, the Financial Ombudsman Service notes that the claim is usually considered first under the escape of water section of the policy. That can change the excess and how the claim is handled.
Damage caused by past coal mining is different again. It isn’t normally dealt with by your home insurer but through the Mining Remediation Authority, which also provides coal mining reports for properties in former mining areas, including much of Yorkshire and the Lancashire coalfield.
Step 2: initial technical inspection
If triage suggests possible subsidence, a surveyor or engineer inspects. They will map the cracking, assess the pattern (diagonal stepping through mortar joints, tapering, inside-outside correspondence), and survey the site: trees and their species, drainage runs, slopes, and the age and construction of the building.
The output is usually one of three views: not subsidence (claim declined, with reasons), subsidence with an obvious cause (move to investigation to confirm), or unclear (investigation needed).
Step 3: investigation
This is where the claim slows down, and where policyholders often lose patience — but it is the most important phase. Typical investigations include:
- CCTV drainage survey — leaking drains are among the most common and most fixable causes
- Boreholes or trial pits — establishing soil type, foundation depth and moisture content
- Root analysis — identifying which vegetation is implicated, and whose
- Level and crack monitoring — precise measurements repeated over months to establish whether movement is ongoing and whether it is seasonal
Monitoring typically runs six to twelve months, sometimes through a full seasonal cycle. This feels glacial when your wall is cracked, but intervening before the cause is proven wastes money and frequently fails.
Step 4: mitigation — addressing the cause
Once causation is established, the cause is removed or managed:
- Vegetation — removal or reduction of the implicated trees. Where a neighbour’s or council tree is involved, this can add months of liaison (and occasionally a recovery claim against the tree owner).
- Drainage — repair or relining of defective drains.
- Heave risk check — before removing a mature tree on shrinkable clay, the risk of the ground swelling as it rehydrates has to be considered. This is why “just cut the tree down” is not always the first move.
In the majority of claims, mitigation plus a period of confirmed stability is enough. Underpinning is the exception, not the rule — it is required only where the ground cannot be stabilised by removing the cause.
Step 5: repair
Once monitoring confirms the building is stable, repairs are scoped and carried out — typically crack repair, re-pointing, replastering and redecoration. Structural repairs such as partial rebuilding or underpinning are specified by an engineer where genuinely needed.
Check the scope carefully before signing it off. Under-scoped subsidence repairs — hairline “making good” over movement damage that needed stitching or re-building — are a recurring source of disputes and repeat claims.
Step 6: the paperwork that matters
At the end of a properly handled claim you should receive documentation, often including a Certificate of Structural Adequacy (CSA) where structural repairs were completed under professional supervision. Keep everything: the investigation reports, monitoring data, scope of works and completion certificates.
This file is what makes the property saleable and insurable later. A documented, investigated, repaired subsidence history is a manageable thing; an undocumented one is a valuation problem.
Where claims go wrong
From the inside, the same failure points recur:
- Causation disputes — “wear and tear”, “settlement” or “pre-existing” declinatures that do not always survive independent scrutiny.
- Investigation drift — monitoring that runs on without decisions being made.
- Under-scoped repairs — cosmetic fixes for structural damage.
- Communication vacuum — months of silence between milestones, leaving policyholders in the dark in a stressful situation.
An independent technical opinion is most valuable at three moments: when a claim is declined on causation grounds, when a repair scope looks thin, and when repairs are complete but you are not confident they are right. That is precisely the gap independent claims consultancy exists to fill — including, where necessary, supporting a Financial Ombudsman Service referral with a proper technical case.
If you disagree with the insurer
Complain to the insurer first, in writing, and keep copies of everything. The insurer normally has eight weeks to send its final response. If you’re unhappy with that response, or eight weeks pass without one, you can refer the complaint to the Financial Ombudsman Service, which is free to use. The Ombudsman will want to see the evidence, and in a subsidence dispute that usually means the technical evidence: the investigation reports, monitoring results and the reasoning behind the insurer’s decision.
An independent report doesn’t change who runs the claim. You stay in charge of it, and the report gives you, or your solicitor, the technical case to put. We don’t notify, negotiate or settle claims for anyone, which are regulated activities; we provide the technical evidence.
The realistic timeline
A straightforward subsidence claim — clear cause, cooperative parties — commonly runs 12 to 18 months from notification to completed repairs. Complex claims run longer. Knowing that at the outset makes the process far less alarming: the pace is a feature of doing it properly, not a sign your insurer has forgotten you.
Further reading: what home insurance usually covers for subsidence, and how long you have to declare it, and whether subsidence devalues a property.
From the survey archive
Cracks in internal finishes.
A long ceiling crack and a crack above a picture rail, from our survey archive. Cracks like these have several possible causes and do not on their own confirm subsidence.
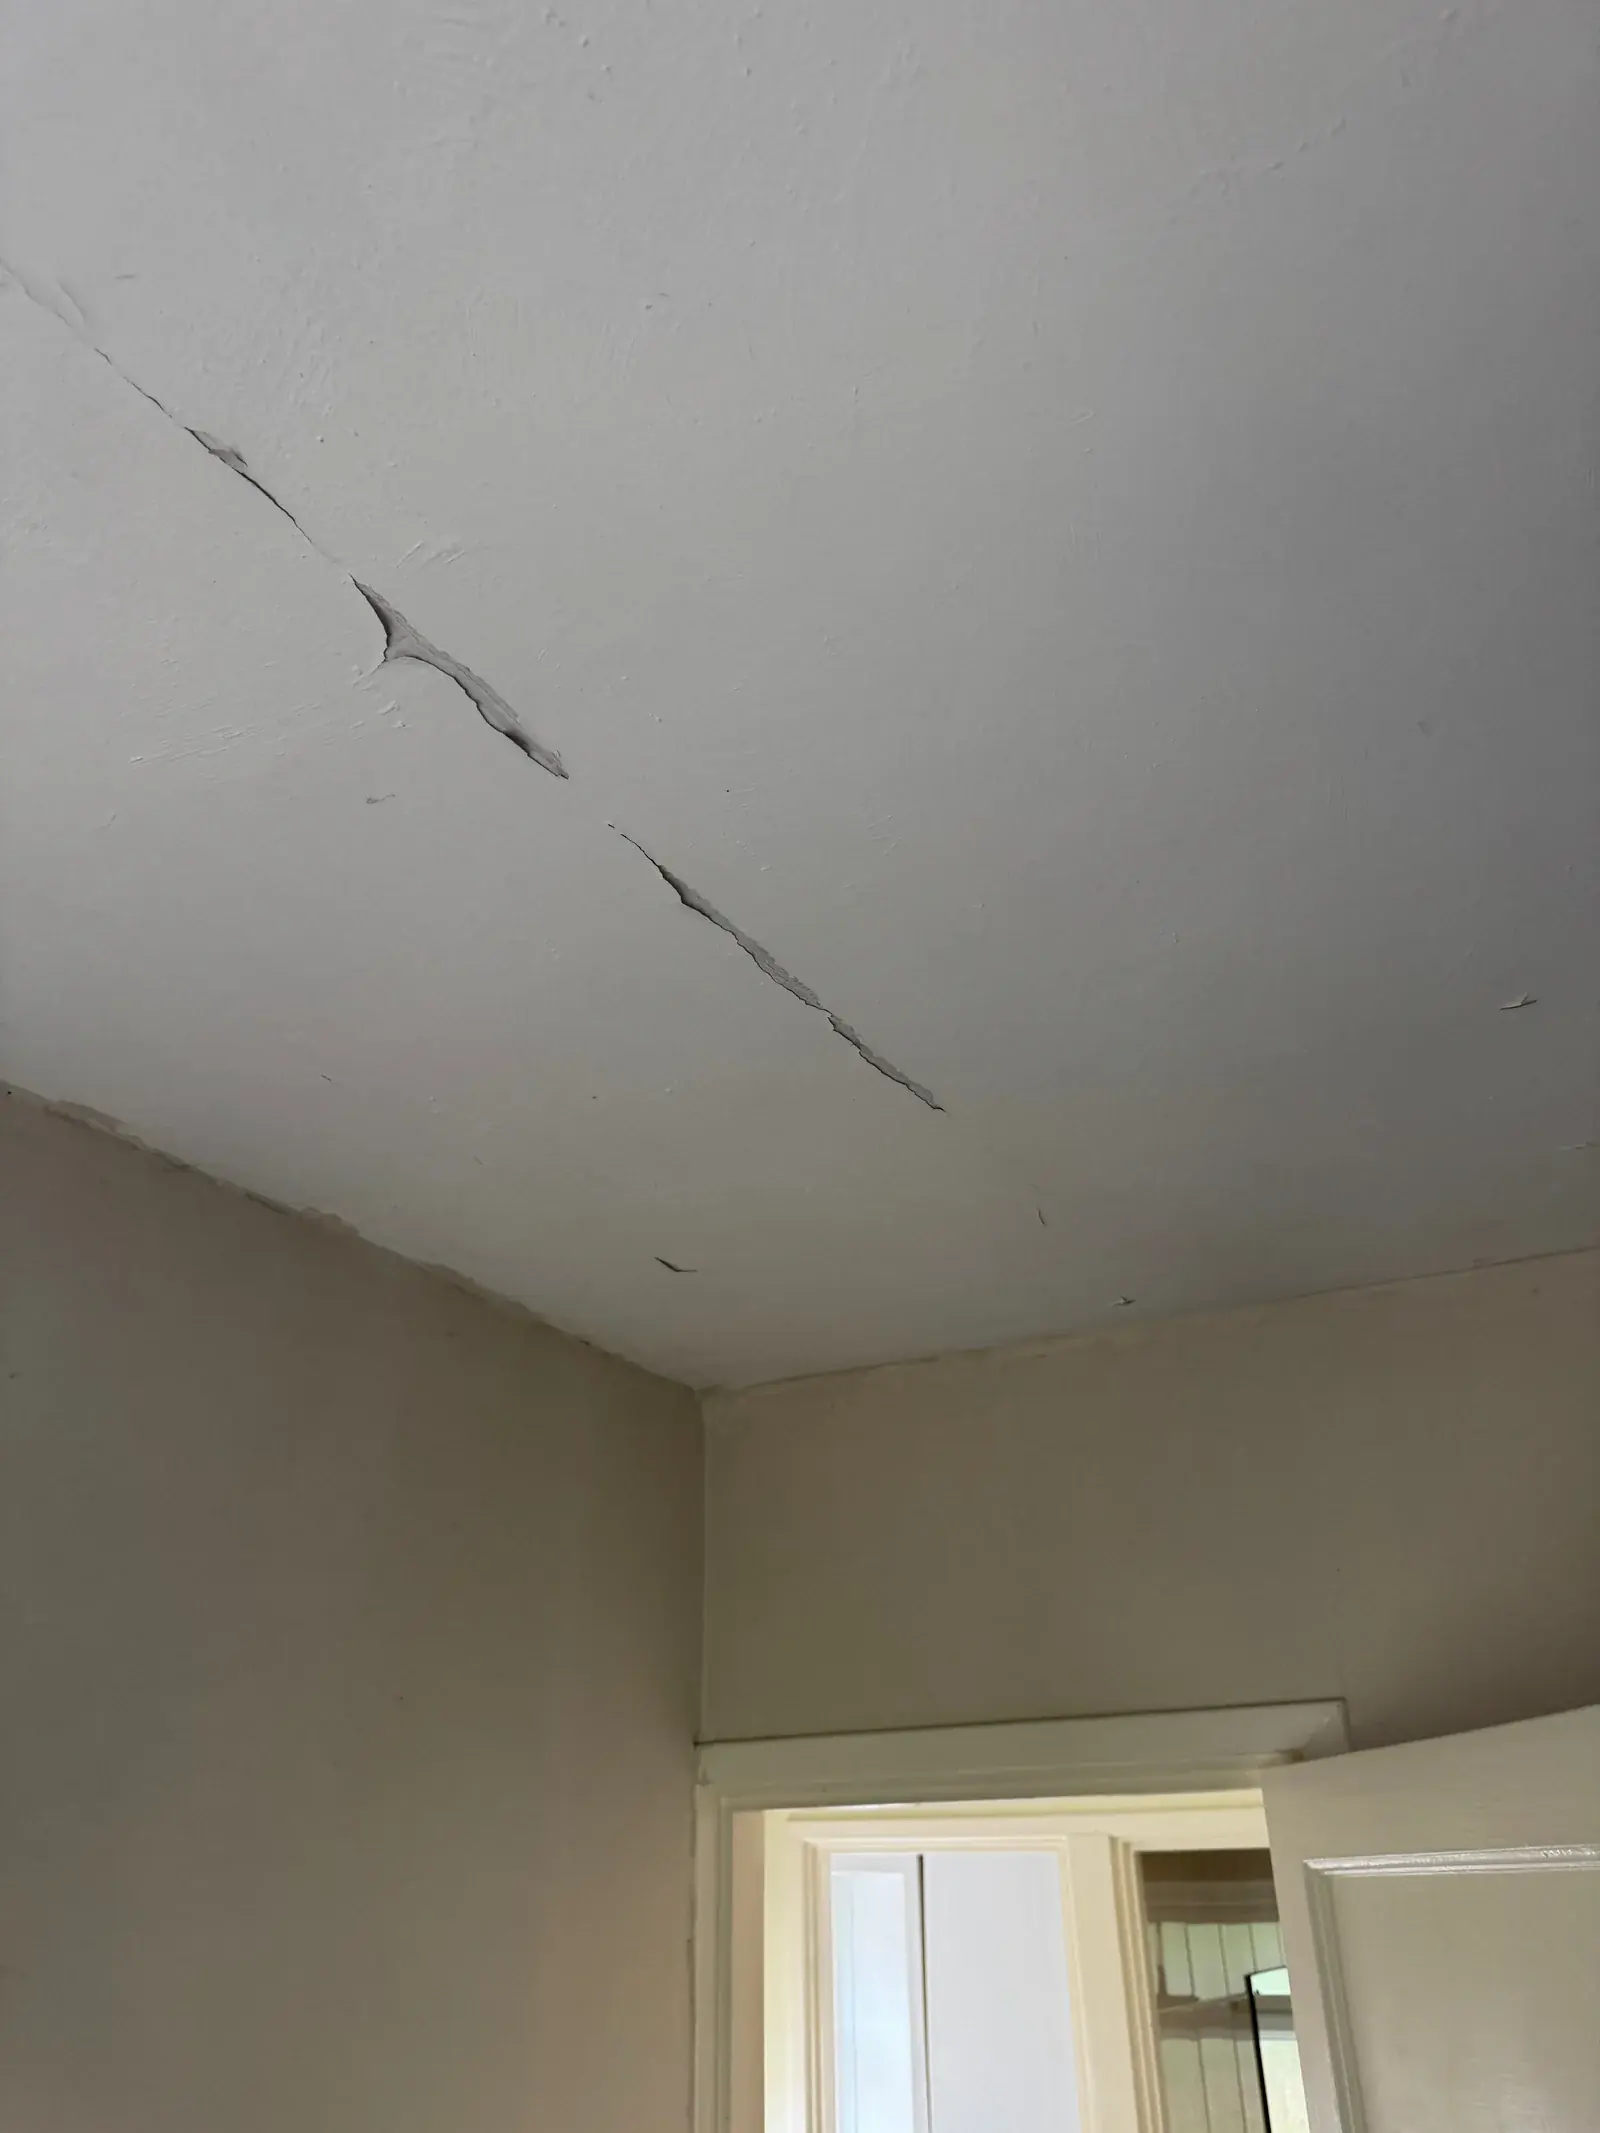
Crack and lifting finish across a ceiling
A long ceiling crack with lifting paint along parts of its length.
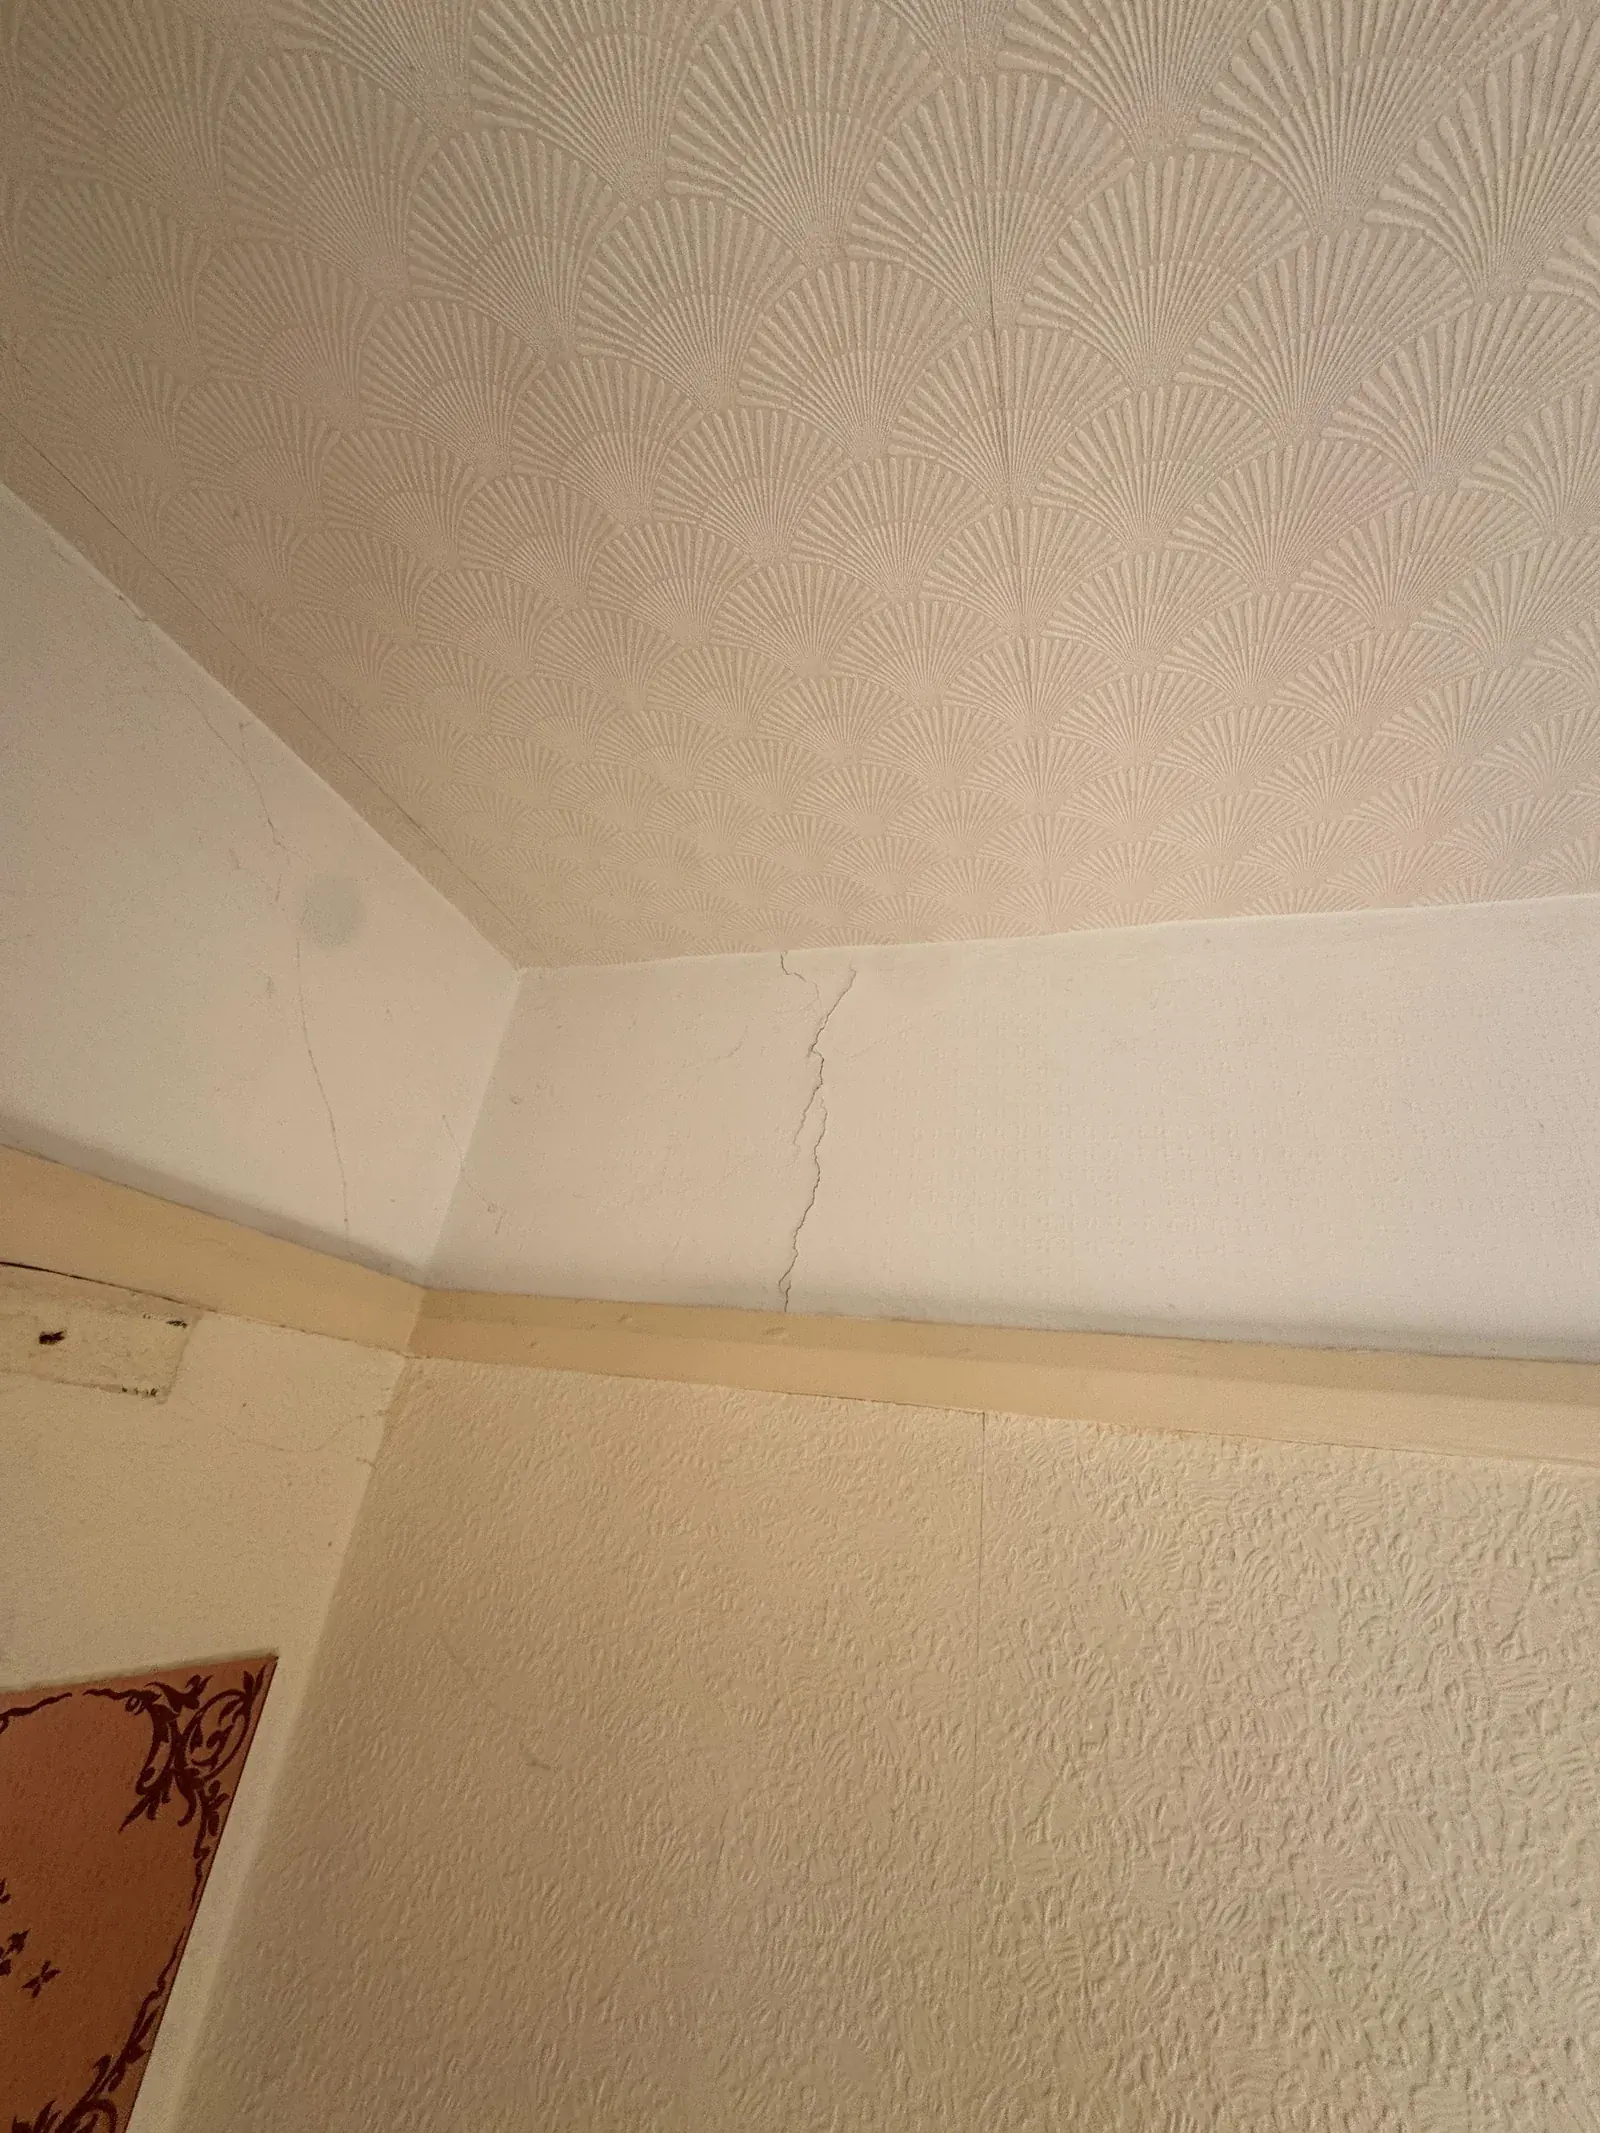
Cracking above a picture rail
An irregular crack across the wall finish between the picture rail and ceiling.
Photographs from our survey archive.
Explore the full photograph collectionRelated service
Independent expert support for policyholders: reinstatement cost assessments, claim validation, technical evidence suitable for an Ombudsman complaint and post-repair inspection.
About this serviceRequest an insurance claims consultancy quoteOr call 01484 218579
RICS-regulated firm no. 9317773
Places where this matters
Towns on the coalfields.
Each of these town pages sets out the local coal mining history and when to ask for a coal mining report.
Free tools
Check your own property.
Sources and further reading
- What to do if subsidence happens — Association of British Insurers
- Domestic subsidence, heave and landslip “change of insurer” claims agreement — Association of British Insurers
- Subsidence and other types of ground movement — Financial Ombudsman Service
- How to complain — Financial Ombudsman Service
- Consumer Insurance (Disclosure and Representations) Act 2012 — legislation.gov.uk
- BRE Digest 251: Assessment of damage in low-rise buildings — BRE
- Check coal mining risk and reports — GOV.UK / Mining Remediation Authority