Start here
Subsidence can affect a property’s value, but there’s no fixed percentage, and the effect ranges from negligible to severe. What decides it isn’t the word “subsidence” in the history. It’s four practical questions a buyer, a lender and an insurer will all ask.
- Repaired, stable
- Certificate of structural adequacy
- Monitoring records
- Insurance transfers
Contents4 sections
The four things that decide the impact
1. Is the movement historic or active?
A house that moved decades ago, was repaired, and has been stable since is a very different proposition from one that’s moving now. Active, unresolved subsidence has the biggest effect on value, because the buyer is taking on an unknown repair and an uninsurable risk. Historic movement that’s been stabilised and repaired has a much smaller effect, and sometimes very little at all.
2. How well was it fixed, and is there proof?
Buyers and lenders want evidence, not assurances:
- a Certificate of Structural Adequacy or equivalent sign-off confirming repairs and stability;
- the engineer’s or loss adjuster’s reports explaining the cause and the fix;
- monitoring records showing movement stopped;
- details of any underpinning, including guarantees.
A well-documented repair after a clear cause (a removed tree, a relined drain) is reassuring. Missing paperwork creates doubt, and doubt costs money in negotiation.
3. Can it still be insured?
This is often the biggest practical issue. A buyer who can’t get reasonable buildings insurance can’t get a mortgage, and a property that can’t be mortgaged has a much smaller pool of buyers. Many insurers will transfer existing cover to a new owner on a property with a subsidence history, which helps enormously. We explain how insurance and declarations work separately.
4. Will a lender lend?
Lenders rely on their valuer and will usually want the paperwork above. Some will lend readily on a properly repaired and insured property; others are more cautious. Where lending is restricted, the market narrows to cash buyers, which puts downward pressure on the price.
Why the answer is different for every house
The effect on value depends on the combination of those factors, plus the local market. In an area where subsidence claims are common (for example, on shrinkable clay, or in former mining areas), buyers and lenders tend to be more familiar with repaired properties. In areas where it’s rare, a history can be more off-putting.
If you’re buying a house with past subsidence
Don’t be scared off automatically, and don’t take it on trust either:
- Get the full history and paperwork from the seller before exchange.
- Check insurability early — ask the current insurer about transferring cover.
- Commission the right survey. A Home Survey Level 3 looks closely at the structure and at signs of renewed movement. Where there’s a specific concern, a subsidence assessment looks at the cause, the repair and whether it’s stable.
- Use what you learn in negotiation. Missing paperwork, an unclear cause or signs of new movement are all legitimate grounds to renegotiate using your survey.
If you’re selling
The best way to protect value is to deal with it properly and document it. Make an insurance claim where it’s genuine, keep every report and certificate, and have them ready for buyers. A clear, complete file turns “subsidence” from a red flag into a resolved history.
Not sure whether a crack is subsidence in the first place? Start with what subsidence actually is, or get in touch with the address and a photo.
From the survey archive
Cracks in brickwork and plaster.
Cracking in brickwork over a window and a crack above a picture rail, from our survey archive. Cracks like these have several possible causes and do not on their own confirm subsidence.
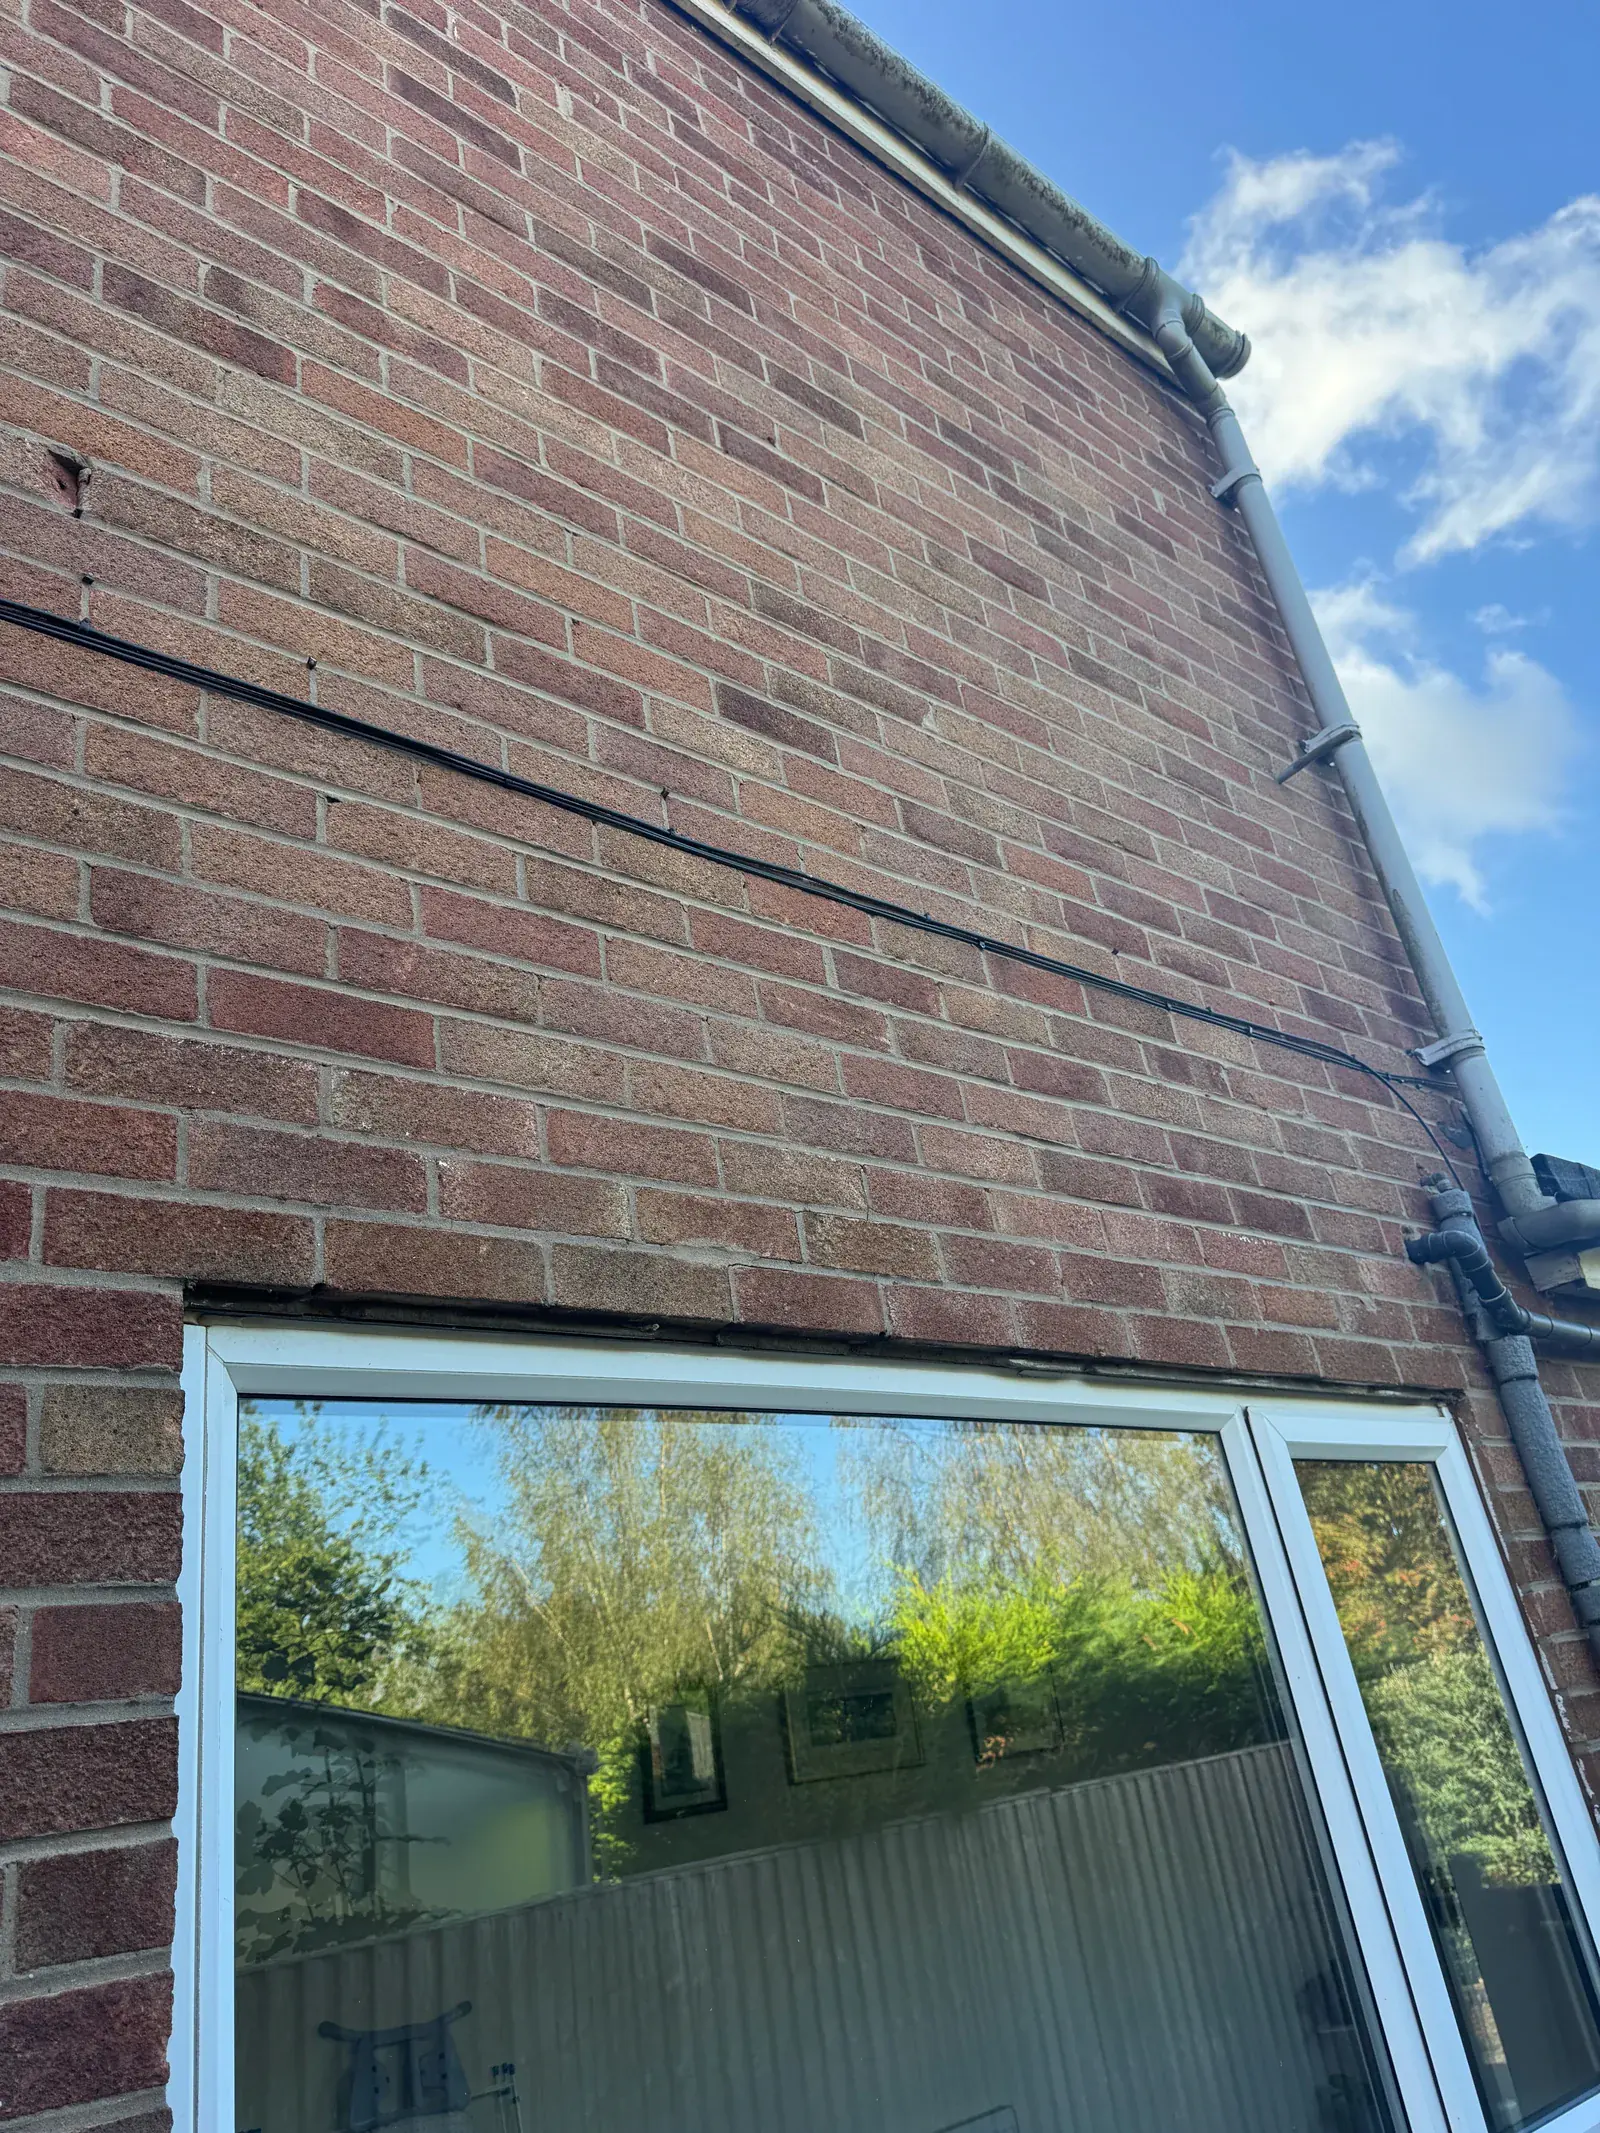
Cracking in brickwork over a window
Cracking in the brickwork above a wide window opening.
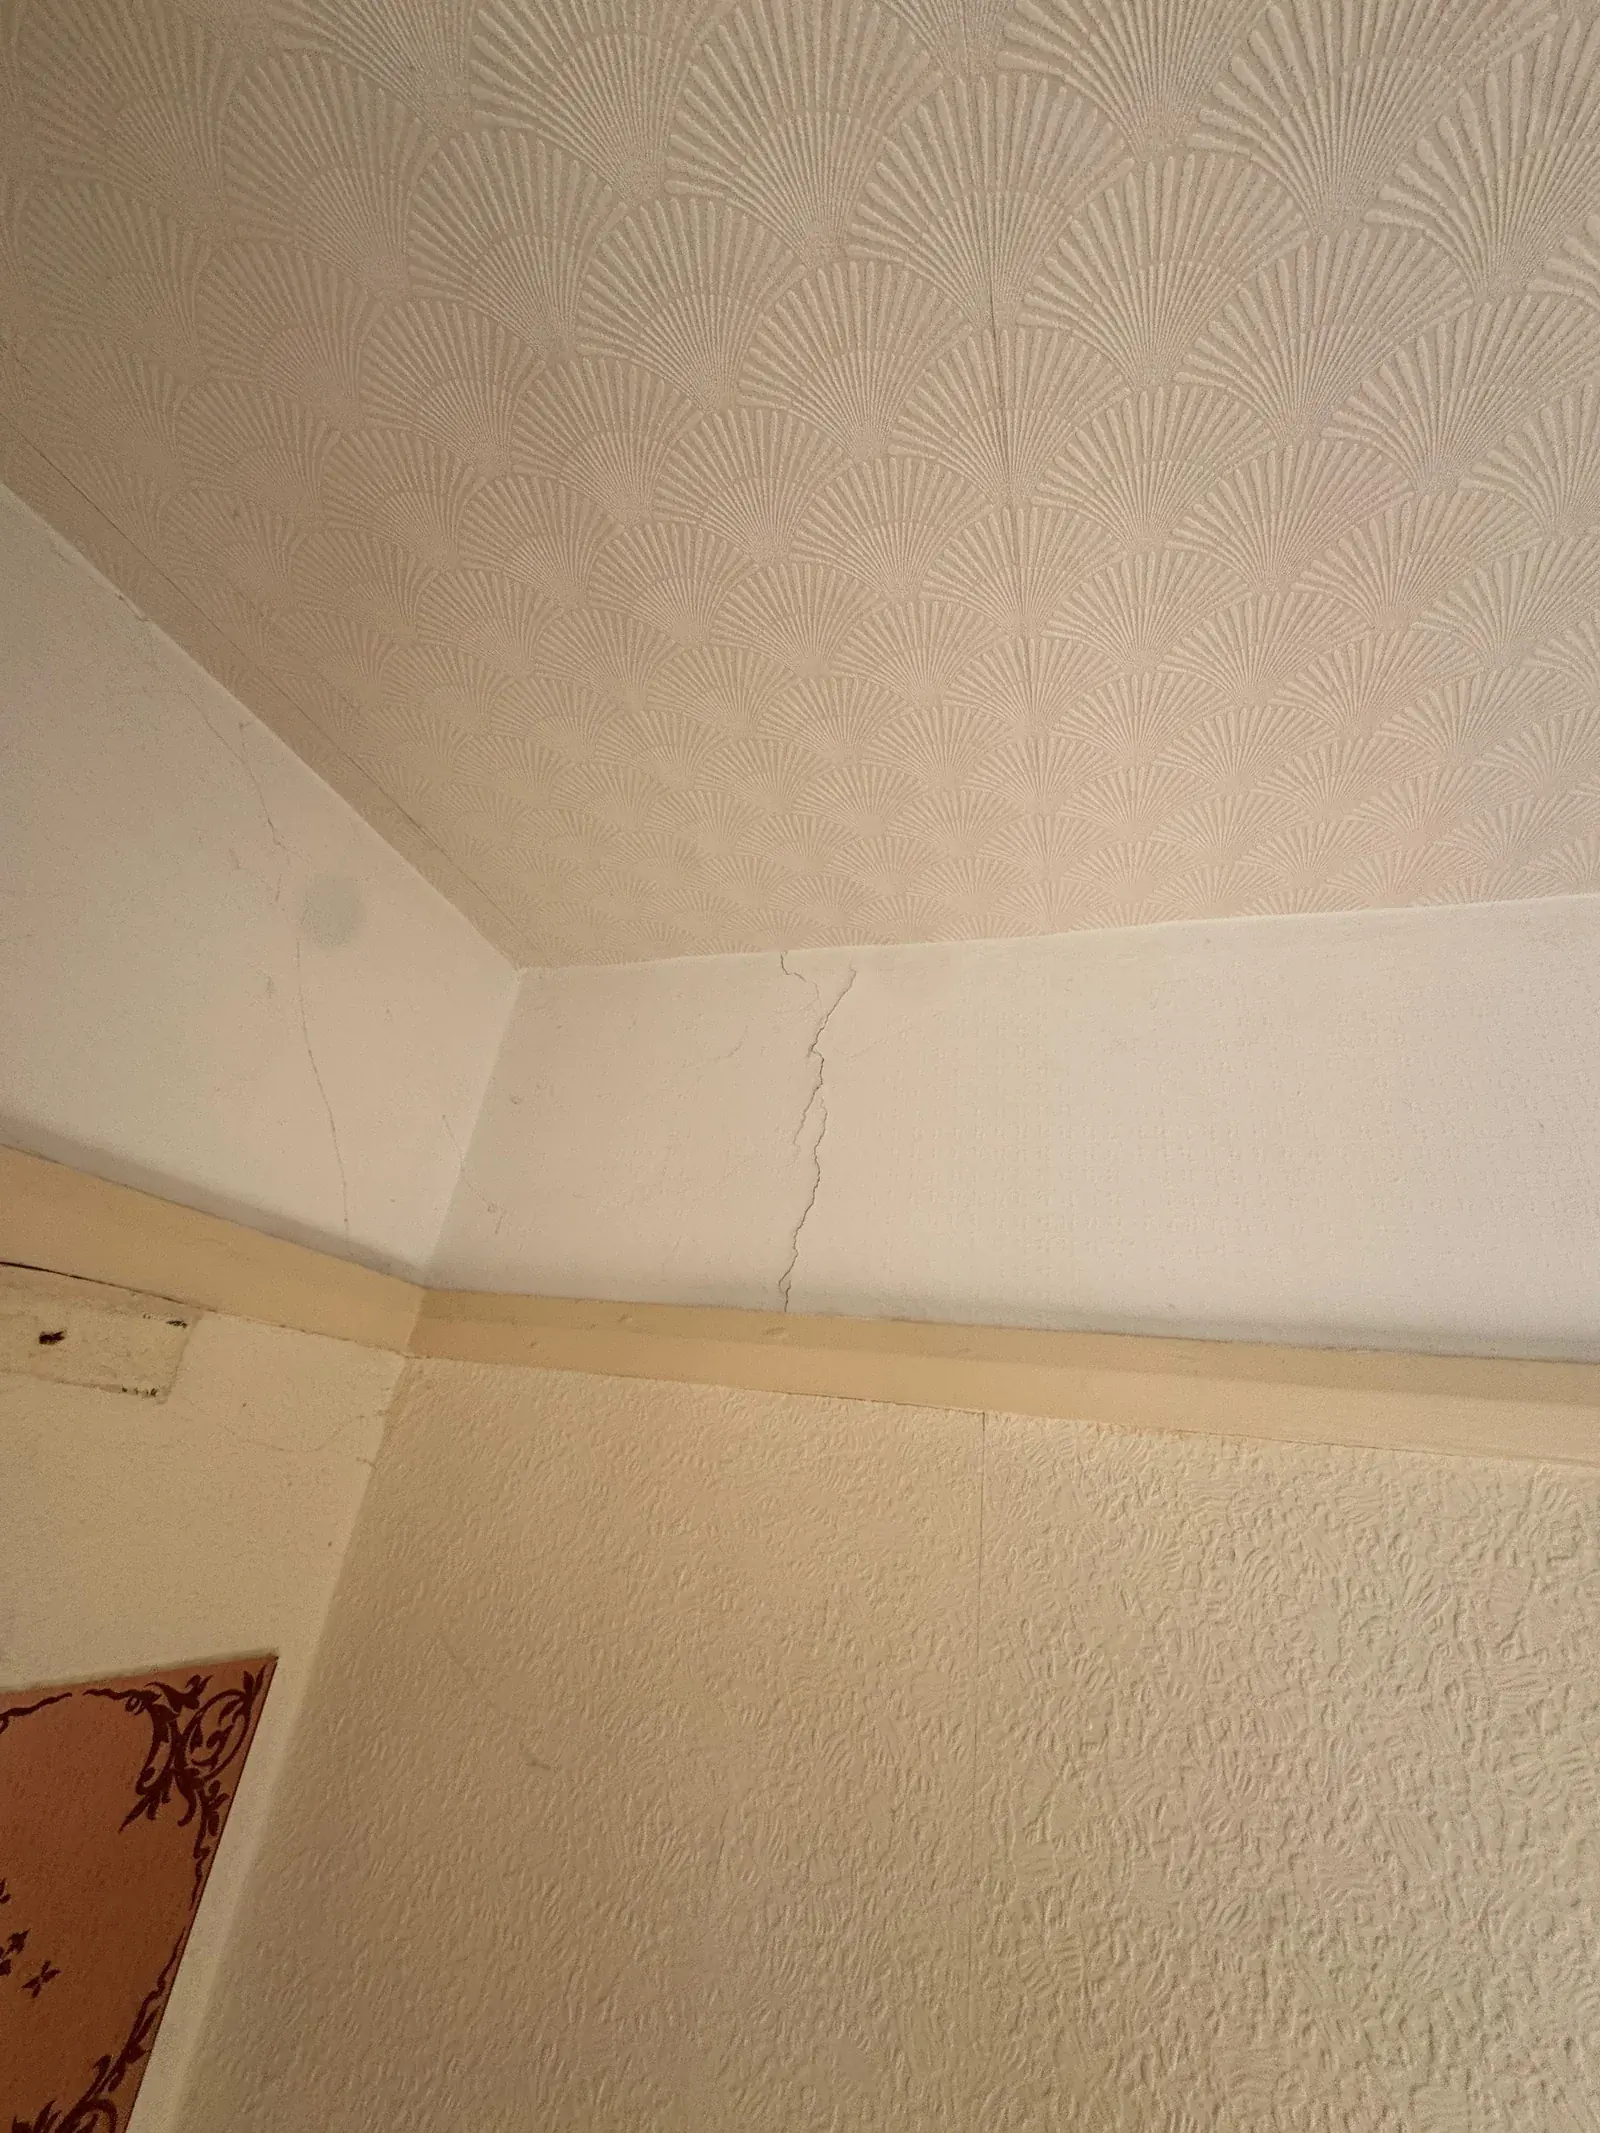
Cracking above a picture rail
An irregular crack across the wall finish between the picture rail and ceiling.
Photographs from our survey archive.
Explore the full photograph collectionRelated service
A subsidence assessment focused on what is causing the movement, built on extensive experience of complex claims, for insurers, policyholders or buyers.
About this serviceRequest a subsidence assessment quoteOr call 01484 218579
RICS-regulated firm no. 9317773
Places where this matters
Towns on the coalfields.
Each of these town pages sets out the local coal mining history and when to ask for a coal mining report.
Free tools