Start here
It’s one of the first questions people ask when they find damp: will the insurance pay? The short answer is that standard home insurance rarely covers damp itself, but it can cover damage caused by a sudden, insured event that leads to damp. The difference between those two is where most claims succeed or fail.
- Failed seal
- Rotted joist
- Sudden
- Storm damage one night
- Gradual
- Months of seepage
This is general guidance. Policies differ, so always read your own policy wording and check with your insurer.
Contents7 sections
What’s usually excluded
Most buildings insurance policies exclude damage that happens gradually, and most damp falls into that category. Typical exclusions include:
- Rising damp, where ground moisture rises through a wall over time.
- Condensation, including mould caused by it.
- Wear and tear and lack of maintenance — for example, water getting in through failed pointing, blocked gutters or a deteriorated roof.
- Gradual leaks that have been happening for a long time.
Insurers treat these as maintenance issues rather than insured events. That’s why identifying which type of damp you have matters: it often determines whether there’s a claim at all.
What may be covered
Where damp is the result of a sudden and unforeseen event that your policy covers, the resulting damage may be claimable. Common examples:
- Escape of water — a burst pipe, a failed tank or a sudden leak from an appliance or fitting, soaking floors, walls and ceilings.
- Storm damage — a roof damaged in a storm lets water in.
- Flood, where the policy covers it.
In these cases, the claim is usually for damage caused by the event, including drying out and repairing affected materials. The cost of repairing whatever caused the leak (the pipe or fitting itself) is often treated differently, so check the wording.
The grey area: slow leaks and hidden damage
Many disputes happen where a leak has been going on unnoticed — under a shower tray, behind a kitchen unit, within a floor void — and the damage is only discovered once it’s significant. Insurers may argue it was gradual; policyholders may argue it was hidden and couldn’t reasonably have been found. How the evidence is gathered and presented matters a great deal here.
From the survey archive
Staining around pipework and fittings.
Staining inside a sink cabinet and darkened floorboards beside a bathroom fitting, from our survey archive.
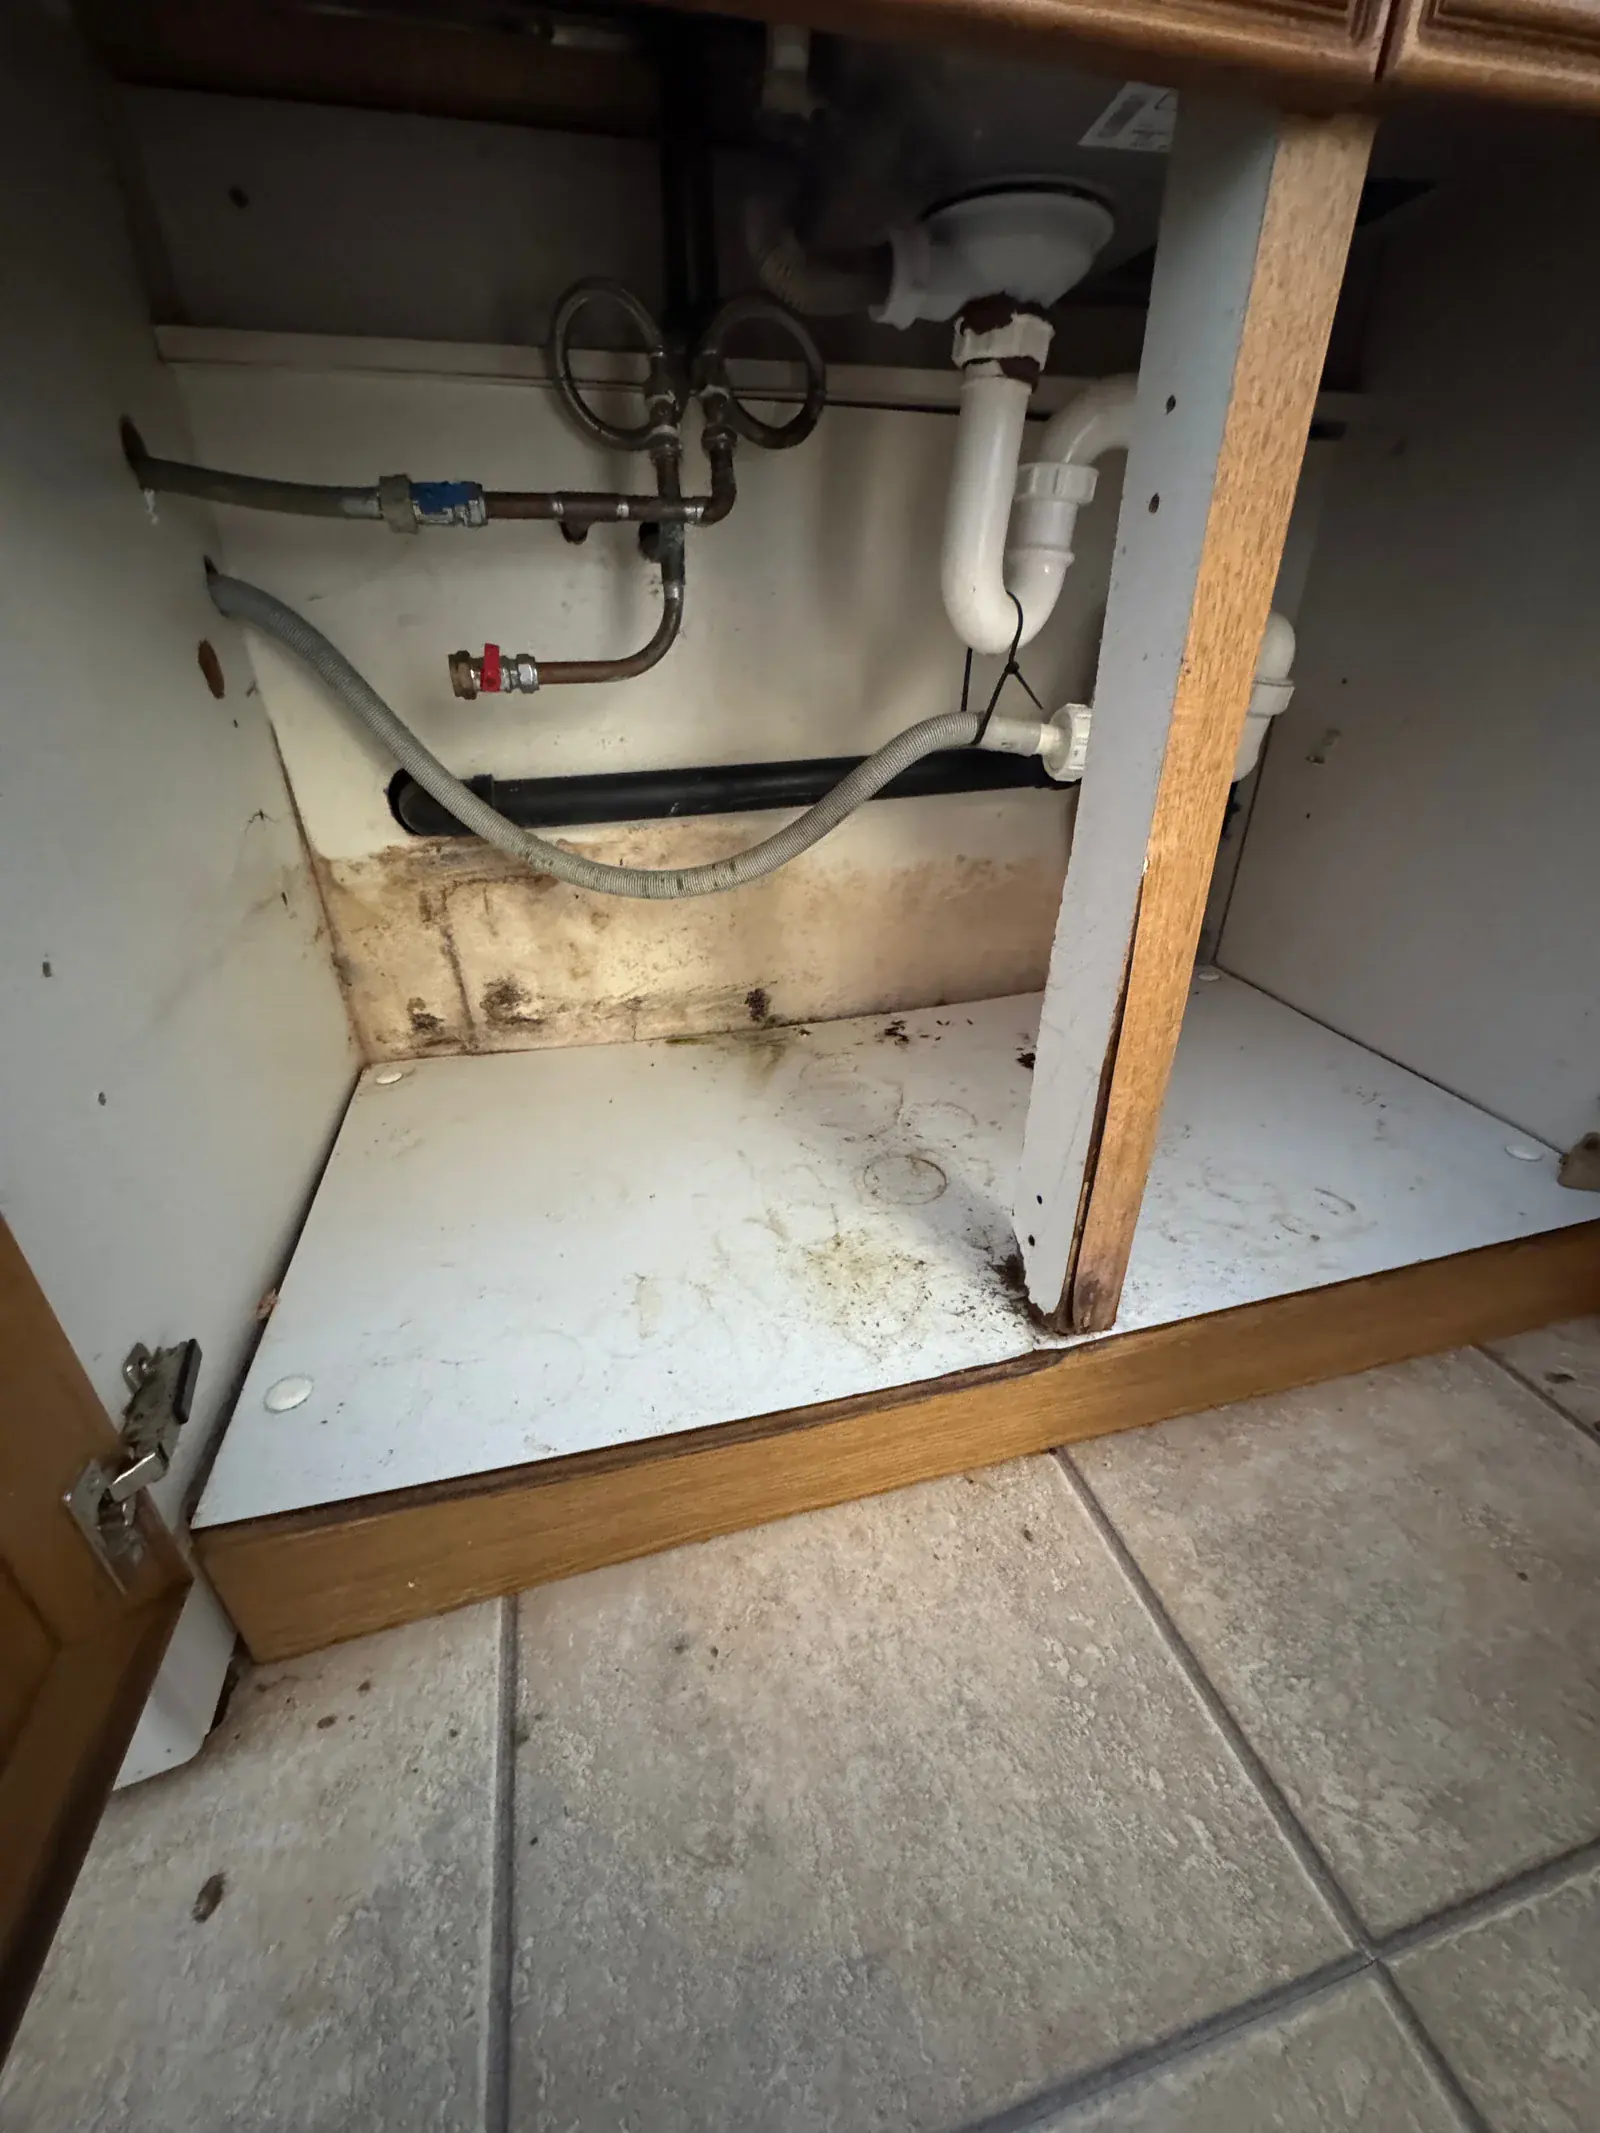
Staining inside a sink cabinet
Staining on the base and back of the cabinet beneath the sink pipework.
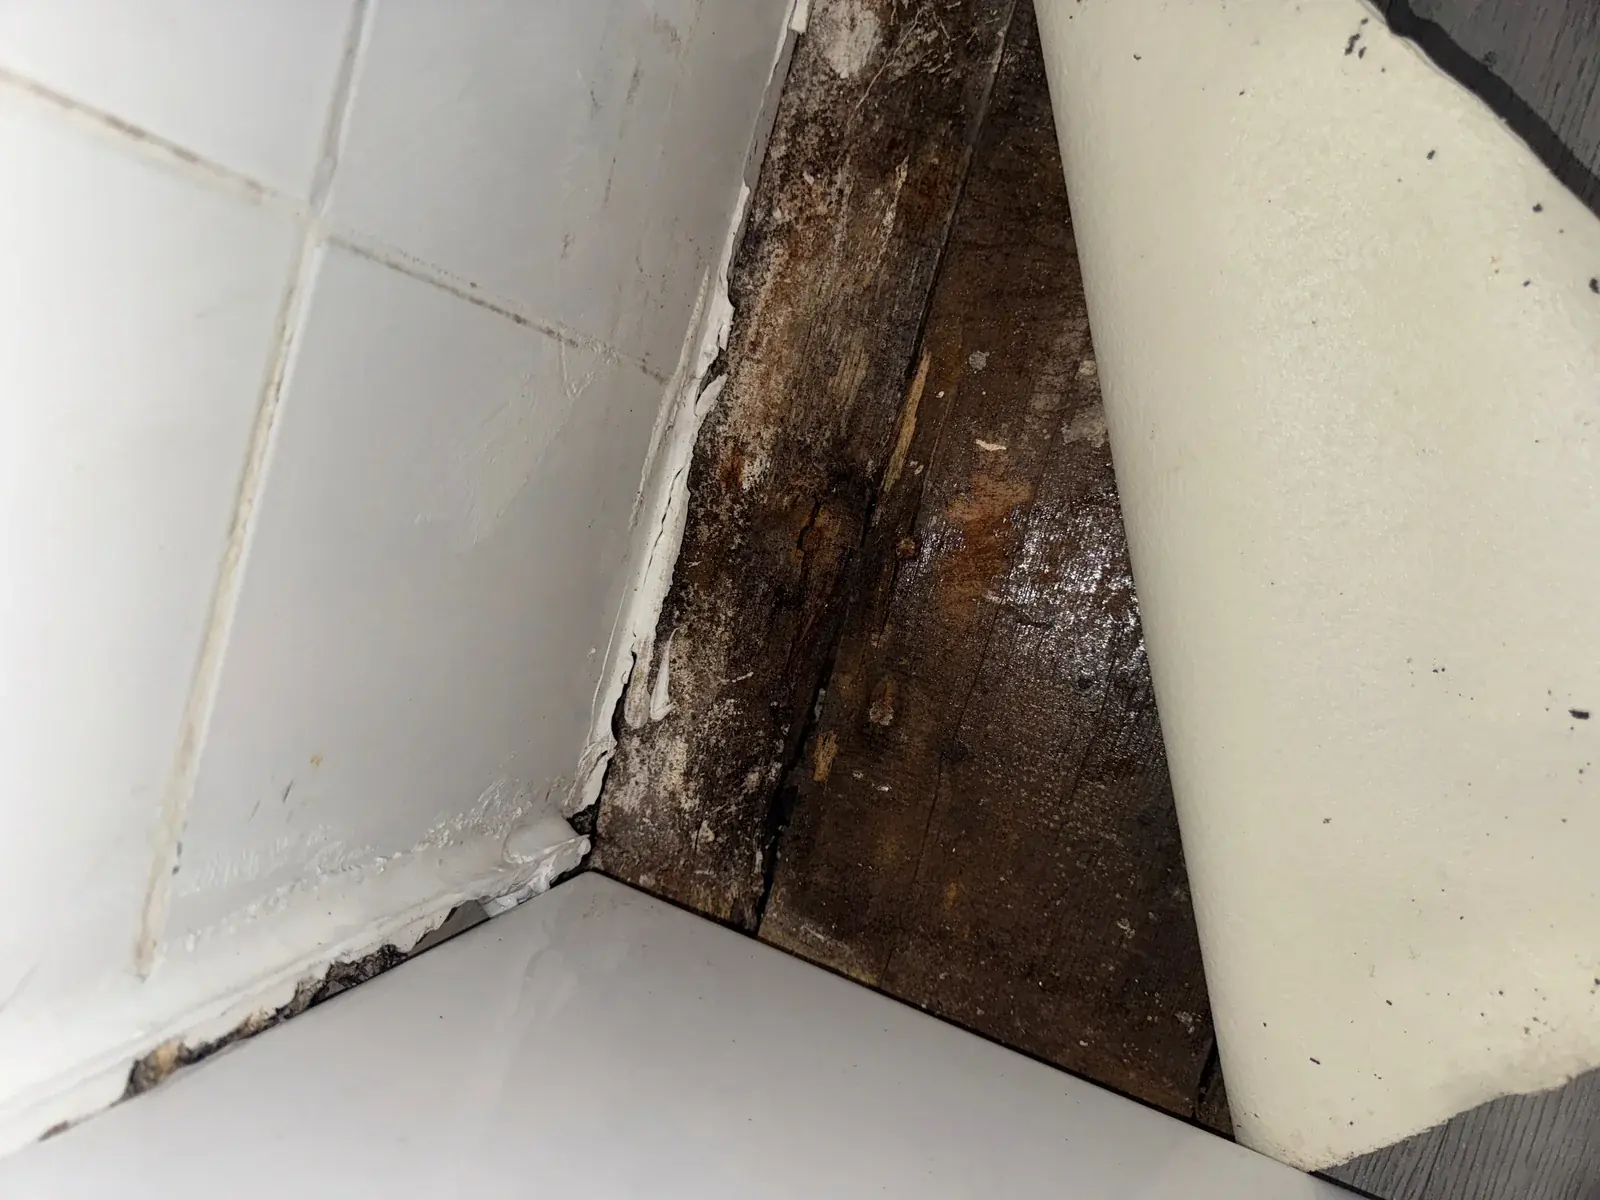
Darkened boards at a bathroom floor edge
Darkened floorboards beneath a lifted covering beside the bathroom wall and sanitary fitting.
Photographs from our survey archive.
Explore the full photograph collectionHow to give a genuine claim its best chance
If you think you have an insurable event:
- Stop the source where you safely can, and prevent further damage. Most policies require you to take reasonable steps.
- Report it promptly. Delay can be used to argue the damage was allowed to worsen.
- Record everything — photographs, dates, what you noticed and when, and any repair invoices.
- Keep damaged materials if possible until the insurer has had the chance to inspect.
- Understand the cause before arguing the case. An independent technical view of what happened, and when, can be the difference between an accepted and a rejected claim.
When a claim is rejected
If you believe a claim has been wrongly turned down, you can complain to the insurer and, if that doesn’t resolve it, take the complaint to the Financial Ombudsman Service. Technical evidence about the cause and timing of the damage is often central to those disputes.
How we help
Through our insurance claims consultancy, we provide policyholders with independent evidence on the cause of damage, the scope of reinstatement and whether the insurer’s position holds up technically. Where the question is simply what’s causing the damp, an independent damp survey answers it. Tell us what’s happened.
Related service
Independent expert support for policyholders: reinstatement cost assessments, claim validation, technical evidence suitable for an Ombudsman complaint and post-repair inspection.
About this serviceRequest an insurance claims consultancy quoteOr call 01484 218579
RICS-regulated firm no. 9317773
Free tools
Check your own property.
Sources and further reading
- Insurance complaints — Financial Ombudsman Service
- How to complain — Financial Ombudsman Service